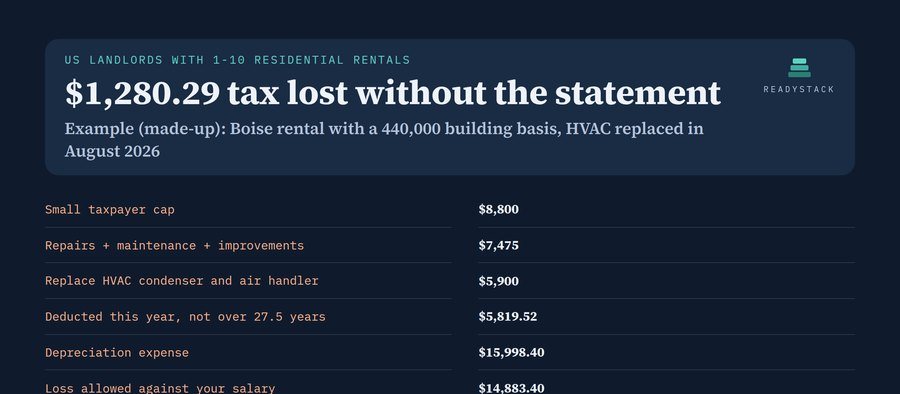
Example (made-up): a Boise landlord’s $5,900.00 HVAC replacement in August 2026 fits under the $8,800.00 small taxpayer cap, so it can be deducted this year; without the safe harbor statement on the 2026 return only $80.48 is, and $1,280.29 of tax is lost at 22%. Repairs, maintenance and improvements on the $440,000 building come to $7,475.00.
Rental bookkeeping apps file the HVAC under CapEx or fixed assets and depreciate it; their pricing pages name no safe harbor test. Here each expense line gets its treatment (repair, routine maintenance, de minimis item, small taxpayer safe harbor or 27.5-year depreciation), your Schedule E lines 3-21 with and without the elections, and how much of the loss the $25,000 passive allowance lets you use at your income. Rules as published by the IRS, read on 2026-11-18.
2026 · 418 Alder Street, Boise, ID 83702
Pro, $79 a year (or $9 a month): print the two election statements with a Schedule E worksheet (or save as PDF) · every rental saved, with one Schedule E CSV for all of them · close the year: next year opens with the suspended loss and every capitalized improvement still depreciating · reminders (.ics) for the return, extension and estimated tax dates · expense ledger CSV · backup.
Pro: $79 a year or $9 a monthEach expense and its treatment
| Date | Expense | Paid | Treatment | Deducted this year | Sch. E line |
|---|
Schedule E, with and without the safe harbor elections
| Line | With elections | Without |
|---|
rental property spreadsheet · 13 inputs · 6 results · repair or improve , safe harbors , Schedule E , passive loss
Pro: statements, every rental, next year
Your rentals
| Rental | Year | Line 21 | Safe harbor | Deducted by elections | Carried on | Improvements depreciating |
|---|
Questions
What does this rental property spreadsheet work out?
From 13 inputs (tax year, filing status, MAGI, your tax rate, active participation, loss carried in, your name, address, building basis, placed-in-service month, AFS, rents and the expense lines) it gives 6 results: whether the small taxpayer safe harbor fits, the amount deducted this year instead of over 27.5 years, the tax lost without the statements, Schedule E line 21, the loss allowed and the loss carried on.
When can an improvement be deducted in one year?
Under the small taxpayer safe harbor (Treas. Reg. § 1.263(a)-3(h)): average gross receipts of $10 million or less, building unadjusted basis of $1 million or less, and the year's total for repairs, maintenance, improvements and similar work on that building at or under the lesser of 2% of the basis or $10,000. You elect it each year with a statement attached to the return.
What if the total goes over the cap?
The cap is a condition on the whole year's total for the building, so the page treats the improvements as capitalized and depreciates them over 27.5 years from the month they were placed in service. In the example with a $360,000 basis the cap is $7,200, the total $7,475.00 is $275.00 over, and the $5,900.00 HVAC is capitalized.
How is the passive loss limit counted?
If you actively participate, up to $25,000 of rental loss can offset other income ($12,500 if married filing separately and living apart). It drops by 50% of MAGI over $100,000 ($50,000) and is gone at $150,000 ($75,000). The rest is suspended on Form 8582 and carried forward. The page assumes this rental is your only passive activity.
What is free and what does Pro add?
Free: one rental and one year, any number of expense lines, all 6 results, every line's treatment and both Schedule E columns on screen. Pro, $79 a year: the election statements and worksheet printed or as PDF, every rental saved, Schedule E CSV, closing the year with the carried loss and depreciation, reminders and backup.
- Sources read on 2026-11-18: IRS, Tangible Property Final Regulations FAQ (irs.gov, updated 04-Aug-2026): de minimis $2,500 / $5,000 per invoice or item, small taxpayer safe harbor limits, routine maintenance "more than once during the 10-year period" · Publication 527 (2025): 27.5 years, straight line, mid-month; appliances, carpets and furniture 5 years; "The 100% special depreciation allowance is restored for qualified property acquired and placed into service after January 19, 2025" · Publications 527 and 925: $25,000 special allowance, $100,000-$150,000 phase-out.
- Assumes the rental is a residential building you own, average gross receipts under $10 million, no real estate professional status and no other passive activity. Depreciation uses the IRS rates (first year by month, 3.636% in years 2-9). Items over the de minimis limit take the 100% bonus depreciation unless you elect out.
- Your data stays in this browser (localStorage). Nothing is sent to us. A calculation and record tool, not tax or legal advice.
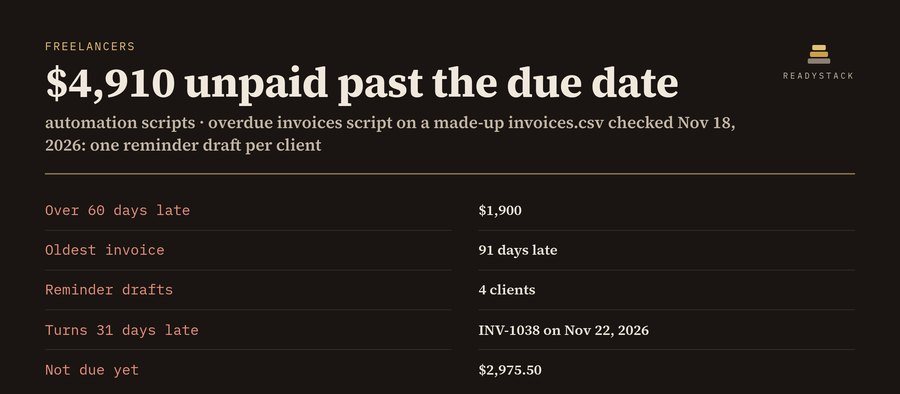 automation scripts | Python: invoices, contacts, bank, files
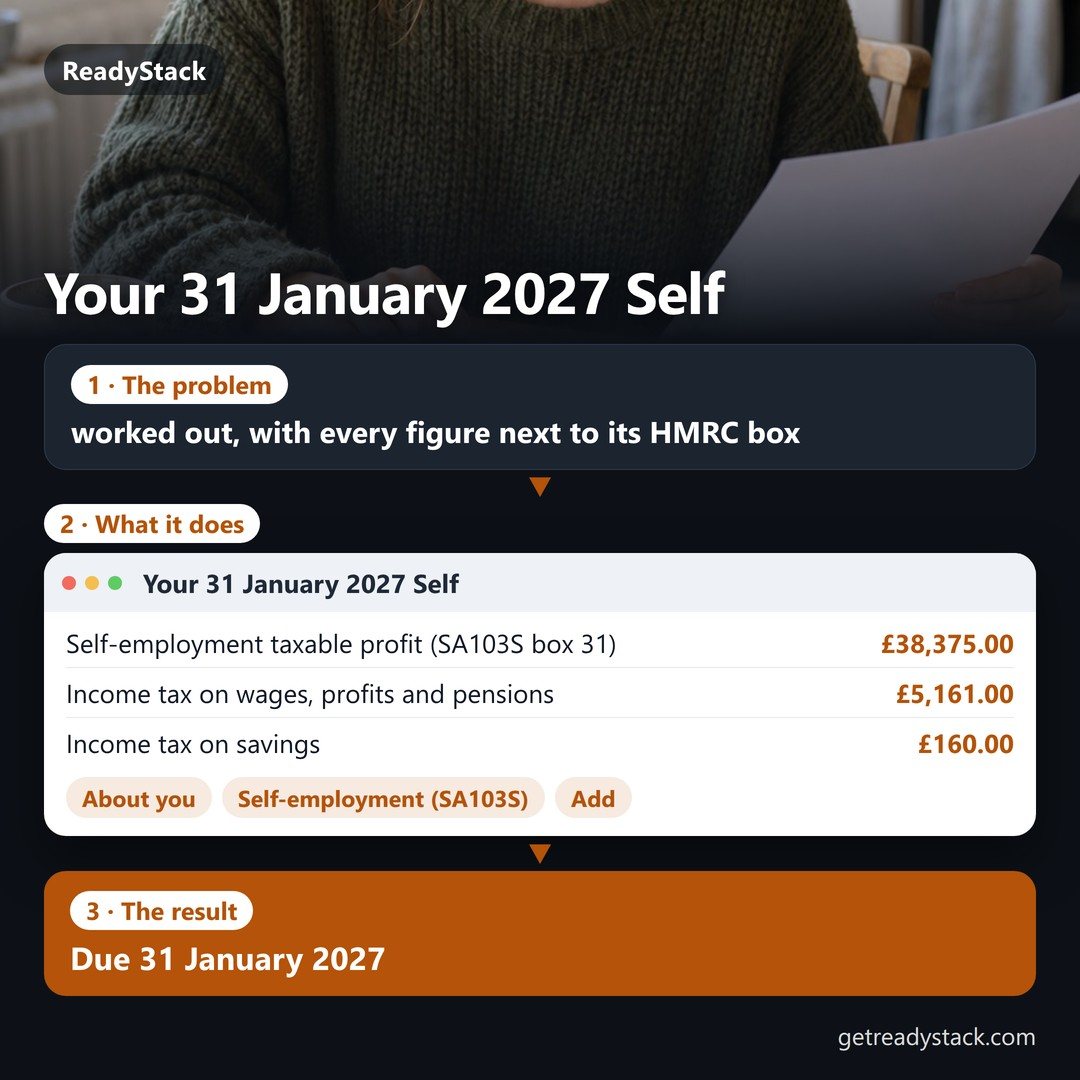
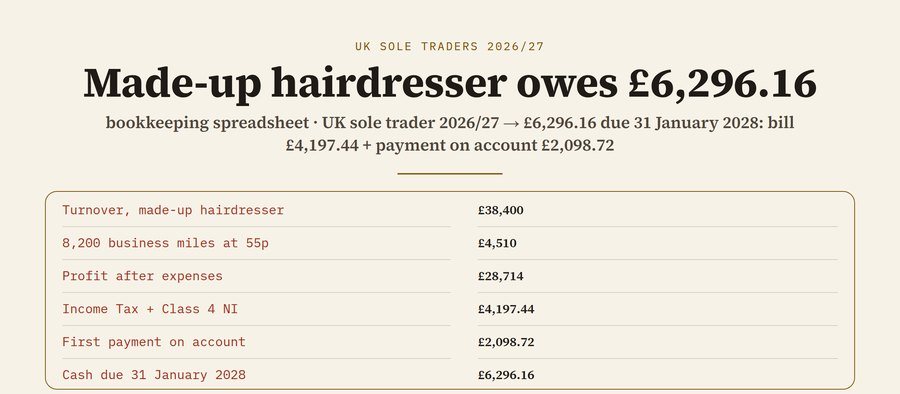 bookkeeping spreadsheet for UK sole traders 2026/27: ledger, SA103S boxes, 55p mileage and the tax to set aside
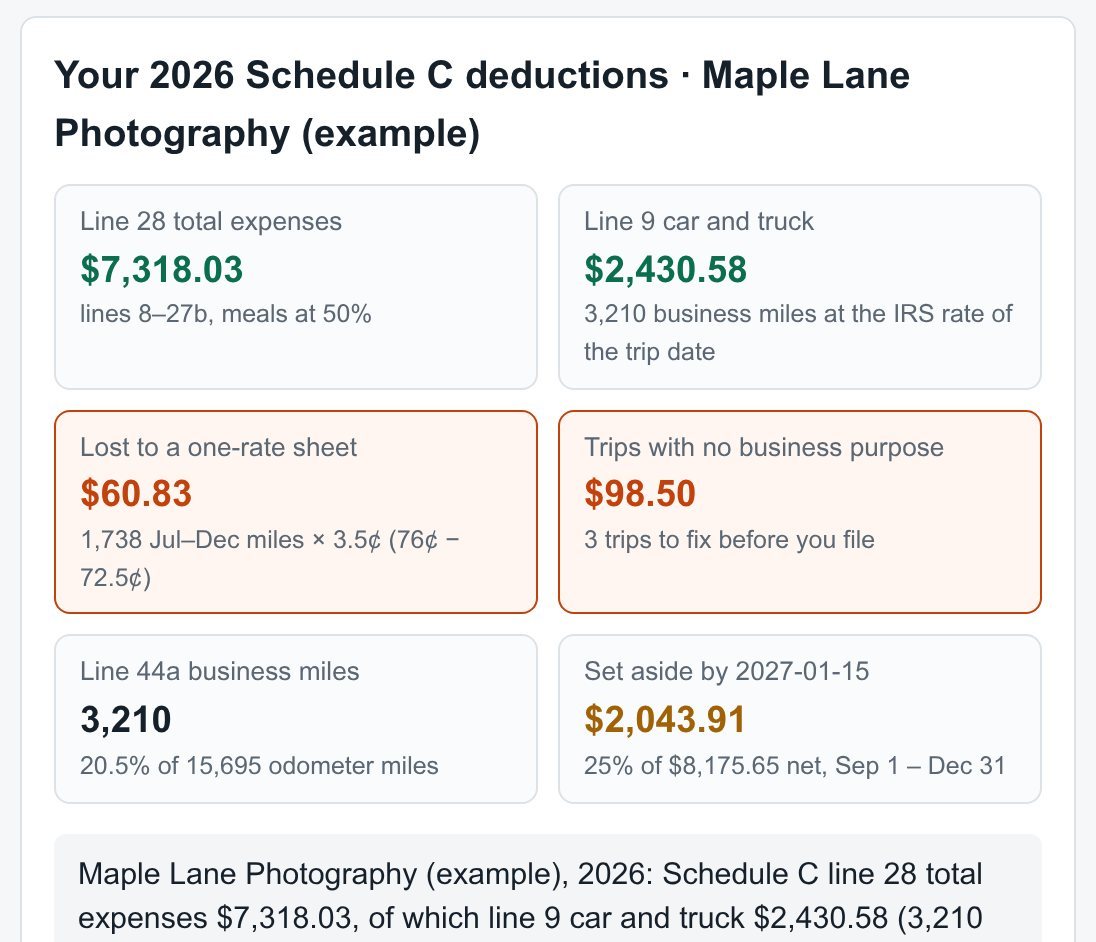 small business planner | Expense & Mileage Tracker | Schedule C 2026 | Estimated Tax Set-Aside
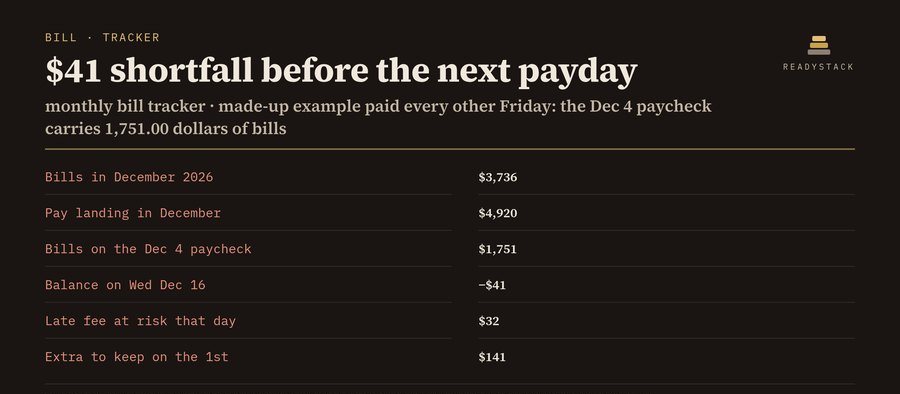 monthly bill tracker | pay-by date, which paycheck, late fee
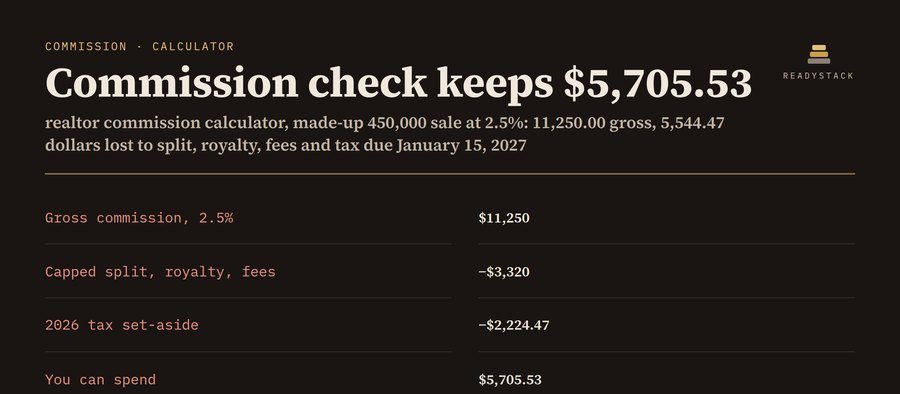 realtor commission calculator | split, cap, royalty, 2026 tax set-aside and due date
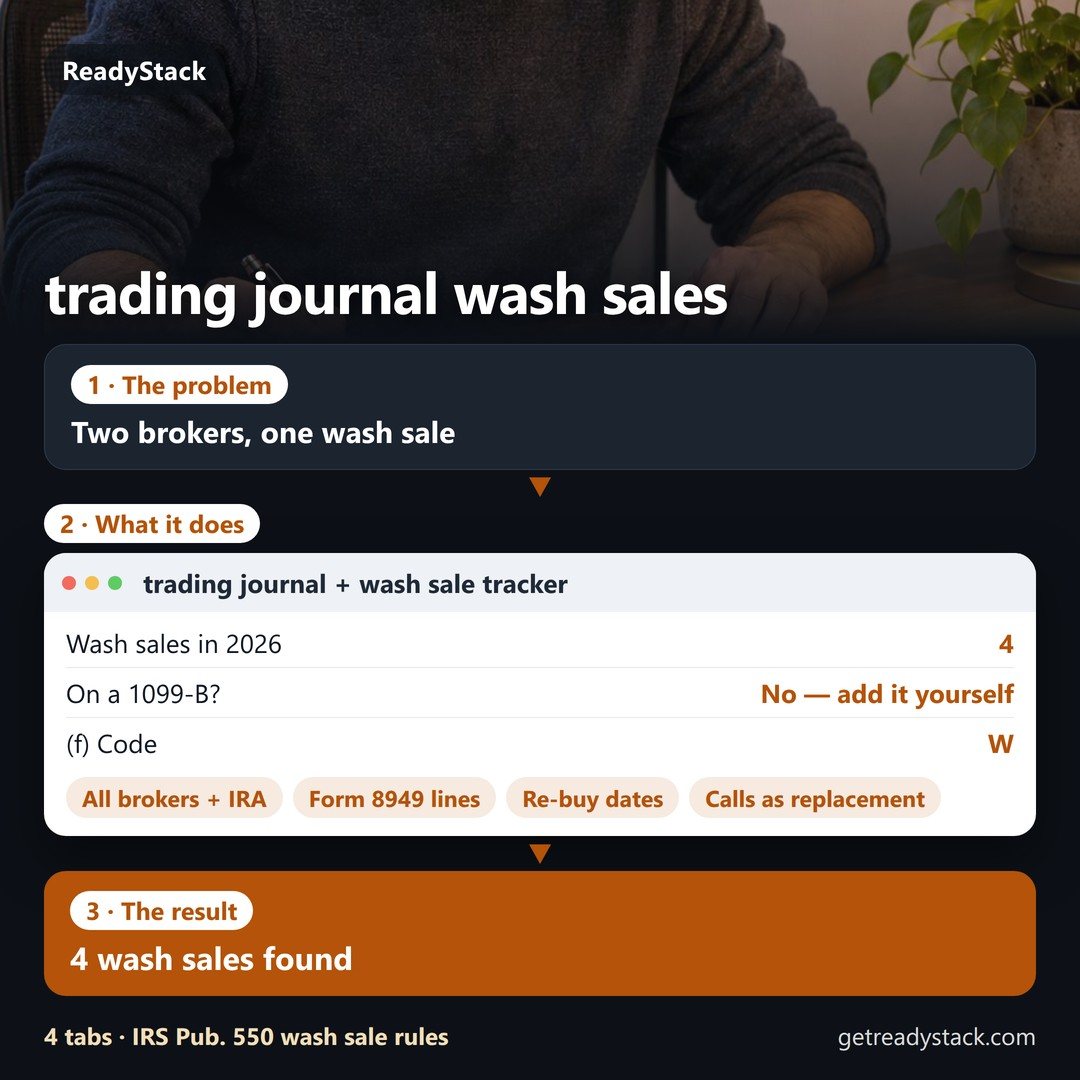 trading journal + wash sale tracker: all brokers, IRA, Form 8949, re-buy dates
 Dividend tracker spreadsheet with withholding tax by country: monthly dividend calendar, yield on cost, DRIP
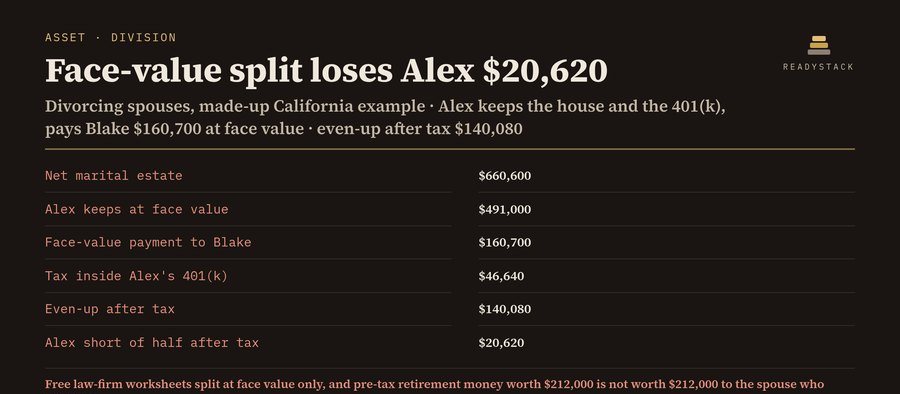 divorce asset division calculator | separate property, equalization, after-tax
 Making Tax Digital for Income Tax penalty points tracker