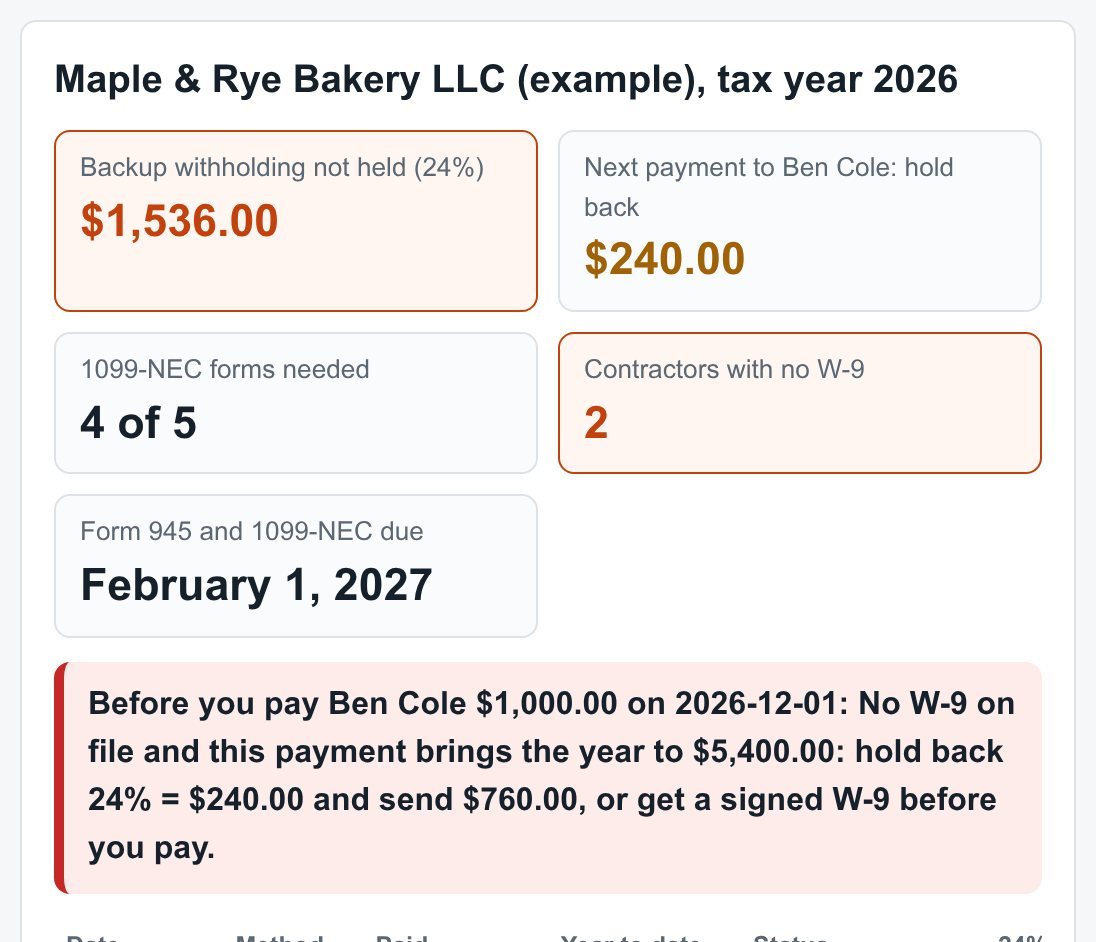
Example (made-up): Maple & Rye Bakery paid Ben Cole $2,700.00 after his year passed the $2,000 line with no W-9 on file, so the 24% backup withholding was never held and the bakery can lose $648.00 to the IRS, which can collect it from the payer. Across its 5 contractors the bakery left $1,536.00 unheld, and before the next $1,000.00 payment to Ben Cole the tracker says: hold back $240.00, send $760.00.
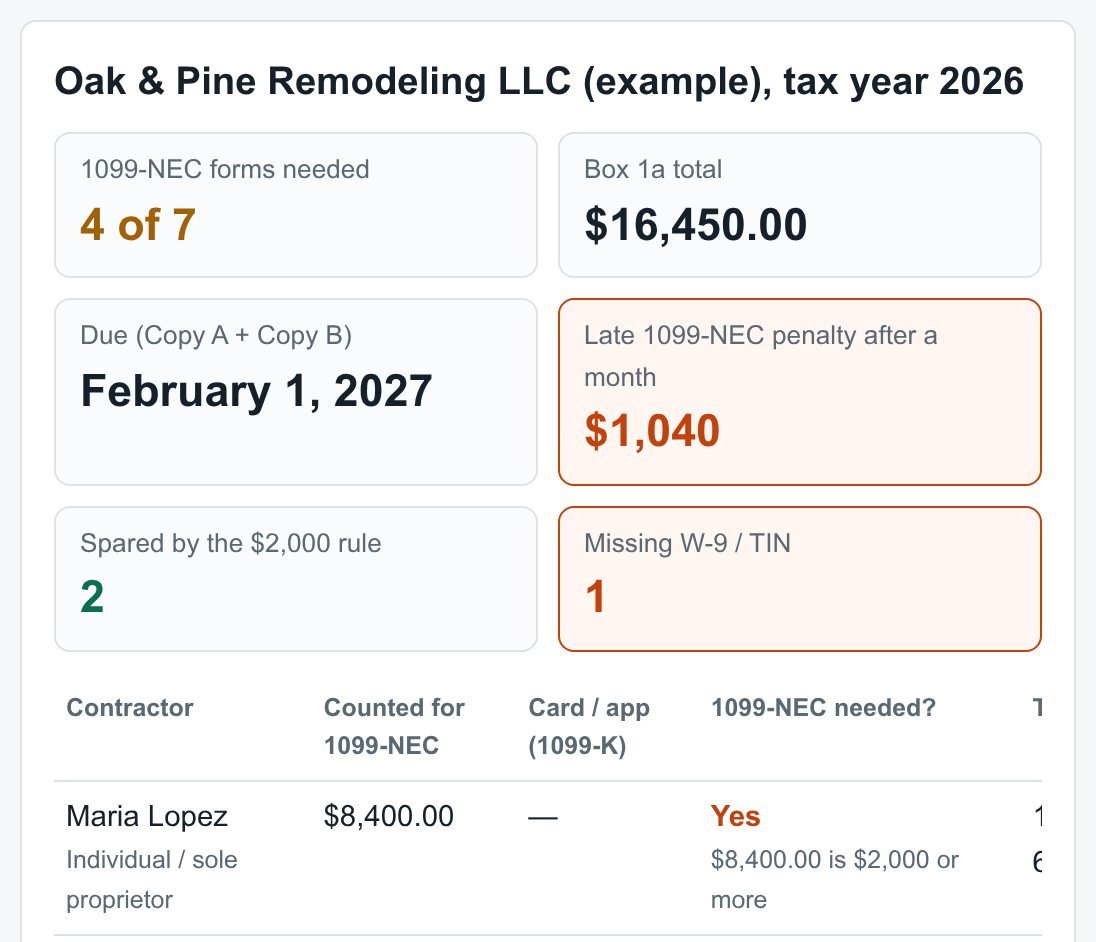
Spreadsheet 1099 trackers add up the year and stop there. This one goes payment by payment: it marks the payment that crosses the $2,000 line (IRS instructions, Rev. 12/2026), checks whether a signed W-9 was on file on that date, applies the rule that the crossing payment and every later one are subject (Treas. Reg. § 31.3406(b)(3)-1), skips the wait for contractors you had to send a 1099 for last year, and leaves card and PayPal payments to Form 1099-K.
Maple & Rye Bakery LLC (example), tax year 2026
Before you pay Ben Cole $1,000.00 on 2026-12-01: No W-9 on file and this payment brings the year to $5,400.00: hold back 24% = $240.00 and send $760.00, or get a signed W-9 before you pay.
| Date | Method | Paid | Year to date | Status | 24% not held |
|---|---|---|---|---|---|
| Ana Ruiz Individual / sole proprietor · W-9: received 2026-01-10 · year total $2,600.00 · subject from 2026-07-08 | |||||
| 2026-02-12 | check | $1,200.00 | $1,200.00 | under the line | — |
| 2026-07-08 | ACH | $1,400.00 | $2,600.00 | W-9 on file | — |
| Ben Cole Individual / sole proprietor · W-9: none · year total $4,400.00 · subject from 2026-09-15 | |||||
| 2026-03-05 | check | $900.00 | $900.00 | under the line | — |
| 2026-06-10 | check | $800.00 | $1,700.00 | under the line | — |
| 2026-09-15 | ACH | $1,200.00 | $2,900.00 | 24% not held | $288.00 |
| 2026-11-02 | check | $1,500.00 | $4,400.00 | 24% not held | $360.00 |
| Cora Diaz Studio LLC LLC (not taxed as a corporation) · W-9: received 2026-08-01 · year total $4,500.00 · subject from 2026-05-01 | |||||
| 2026-02-01 | check | $1,500.00 | $1,500.00 | under the line | — |
| 2026-05-01 | check | $1,500.00 | $3,000.00 | 24% not held | $360.00 |
| 2026-09-01 | ACH | $1,500.00 | $4,500.00 | W-9 on file | — |
| Dev Patel Individual / sole proprietor · W-9: none · 1099 filed for last year: no wait for the line · year total $2,200.00 · subject from 2026-04-20 | |||||
| 2026-04-20 | Zelle | $900.00 | $900.00 | 24% not held | $216.00 |
| 2026-10-12 | check | $1,300.00 | $2,200.00 | 24% not held | $312.00 |
| Eli Brooks Individual / sole proprietor · W-9: none · year total $0.00 | |||||
| 2026-08-20 | PayPal | $2,500.00 | — | card/app: 1099-K | — |
Fix before the next payment
- Ben Cole: no W-9. $648.00 should have been held. Ask for a signed Form W-9 before the next payment; once it is on file, later payments are paid in full.
- Dev Patel: no W-9. $528.00 should have been held. Ask for a signed Form W-9 before the next payment; once it is on file, later payments are paid in full.
- Cora Diaz Studio LLC: the W-9 came on 2026-08-01, after 1 payment(s) that were already subject ($360.00 not held).
- Backup withholding for the year is under $2,500, so no deposits are due during the year: pay it with Form 945 by February 1, 2027.
Summary
Maple & Rye Bakery LLC (example), tax year 2026: 4 of 5 contractors need a 1099-NEC (line $2,000). Backup withholding not held: $1,536.00 (24% of $6,400.00 paid with no W-9 on file: Ben Cole $648.00, Cora Diaz Studio LLC $360.00, Dev Patel $528.00). You can be liable for that amount yourself; it is reported on Form 945, due February 1, 2027. W-9 missing: Ben Cole, Dev Patel. $2,500.00 paid by card or payment app is left to Form 1099-K. Next payment to Ben Cole ($1,000.00): hold $240.00, send $760.00. 1099-NEC due February 1, 2027.
Pro, $52.77 a year (or $7.99 a month): keep every business and every year in one log · carry contractors into the next year with the last-year 1099 mark set · import payments from a bank or bookkeeping CSV · W-9 request letters (print) · reminders in your calendar (.ics) · month-by-month Form 945 record (print) · CSV of every payment with the 24% column.
Pro: $52.77 a year or $7.99 a month1099 tracker 2026 · 7 inputs · 5 results · 24% backup withholding · $2,000 line · W-9 date per contractor · Form 945 and 1099-NEC due February 1, 2027
Pro: keep, carry, remind
My log
| Business · year | 24% not held | 1099-NEC forms | No W-9 | Due |
|---|
Questions
What does this 1099 tracker work out?
From 7 inputs (tax year, your business, contractor list with W-9 dates, payment log, and the next payment's contractor, date and amount) it shows 5 results: backup withholding not held, what to hold back on the next payment, 1099-NEC forms needed, contractors with no W-9, and the Form 945 and 1099-NEC due date. In the made-up example: 1,536.00 dollars, 240.00 dollars, 4 of 5, 2, February 1, 2027.
When does backup withholding start on a contractor with no W-9?
With the payment that brings the contractor's total for the year to the line, and every payment after it. For tax years after 2025 the line is 2,000 dollars (IRS instructions, Rev. 12/2026). Treas. Reg. 31.3406(b)(3)-1 says the whole crossing payment is subject, not only the part above the line. Once a signed W-9 is on file, later payments are paid in full.
Why does the tracker ask whether I sent a 1099 last year?
The regulation drops the wait for the line when you were required to file a 1099 for that same payee for the preceding year. Then backup withholding applies from the first payment of the new year if there is still no TIN on file. In the example, Dev Patel's 2,200.00 dollars are all subject: 528.00 dollars instead of 312.00.
What happens if I did not hold back the 24%?
The IRS General Instructions say a payer who does not collect and pay over backup withholding may become liable for the uncollected amount. The tracker shows that amount per contractor and per payment. Backup withholding is reported on Form 945; for 2026 it is due February 1, 2027, or February 10 if every deposit was made on time.
I paid some contractors by card or PayPal. Do those count?
No. Payments by credit card, debit card or a payment app such as PayPal or Venmo are reported by the payment company on Form 1099-K, so the tracker leaves them out of the line and out of the 24% check. In the example, Eli Brooks was paid 2,500.00 dollars by PayPal and needs no 1099-NEC from the bakery.
Sources, read 2026-11-15: IRS Instructions for Forms 1099-MISC and 1099-NEC (Rev. 12/2026), “Increase in threshold … and backup withholding”: $2,000 for tax years beginning after 2025 · IRS General Instructions for Certain Information Returns, part N (24% rate; “you may become liable for any uncollected amount”) · Treas. Reg. § 31.3406(b)(3)-1(b)(3) · Instructions for Form 945 (2026): file by February 1, 2027. Your data stays in this browser. A record-keeping and calculation tool, not legal or tax advice.
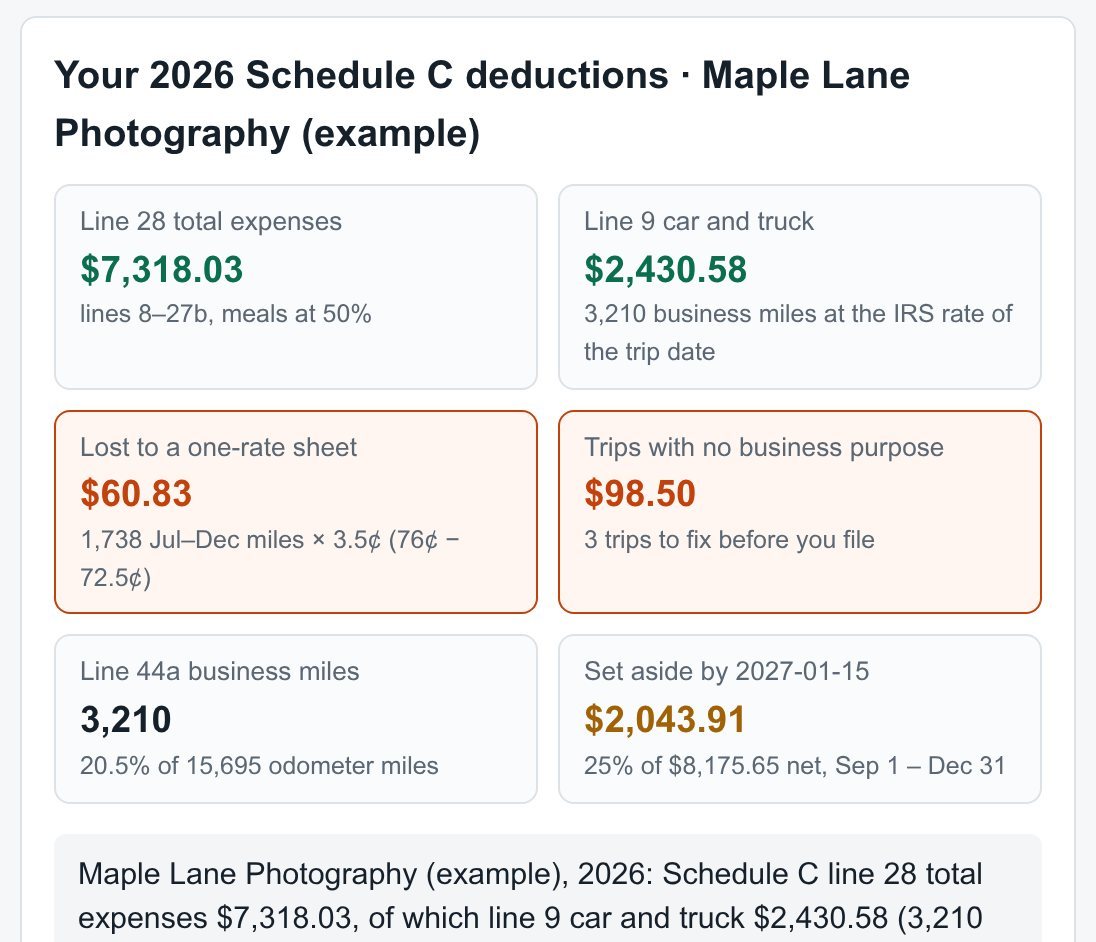 small business planner | Expense & Mileage Tracker | Schedule C 2026 | Estimated Tax Set-Aside
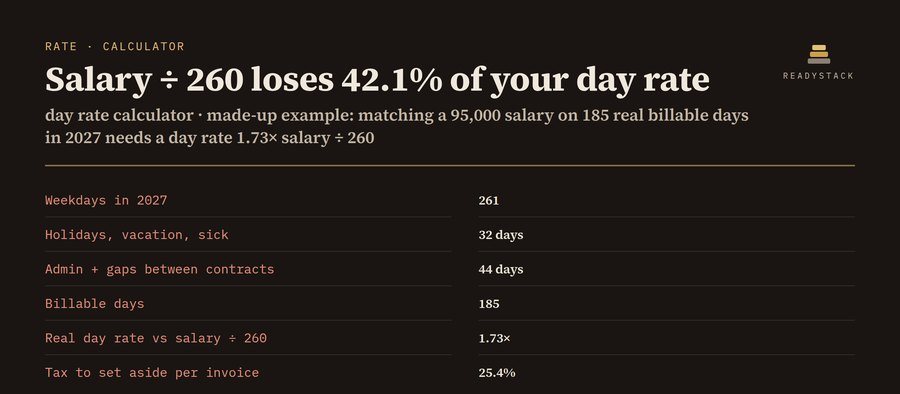 day rate calculator | freelance tax & billable days · US 2027 · UK 2026/27
 mileage tracker for employee reimbursement | IRS rate by trip date, wages check, payroll CSV
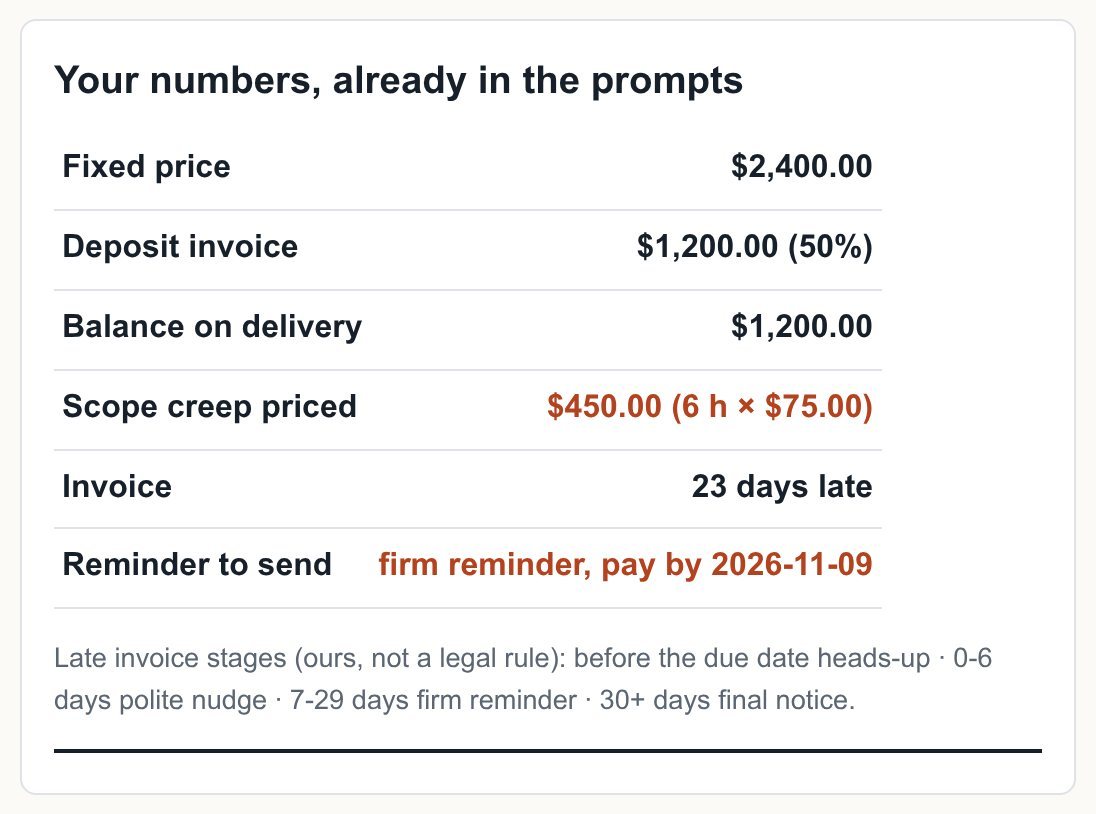 AI prompt packs for freelancers: pitch to paid invoice
 Client portal and CRM for freelancers: proposals, contracts and invoices in one place
 Your January 15 estimated tax payment, worked out from your own month.
 MTD for Income Tax quarterly update: bridging-ready CSV