· ReadyStack
Worked example
Real numbers from this tool, line by line.
You paid a contractor in 2026 and the W-9 never came back. Maybe you asked once, maybe the invoice just got paid. In January the question arrives: what do you owe for the payments you made without a taxpayer identification number on file?
Two rules changed or stayed put, and most answers online mix them up.
The threshold moved. Section 70433 of the One Big Beautiful Bill Act raised the 1099-NEC reporting threshold from 600 to 2,000 for payments made after December 31, 2025. The same section moved the backup withholding trigger in IRC 3406 to the same 2,000. So a contractor you paid 1,800 in 2026 needs no 1099-NEC and no backup withholding. A contractor you paid 18,500 does.
The rate did not move. Backup withholding is 24% of each reportable payment you make while the payee has not given you a TIN. For nonemployee pay there is no 60-day grace for a W-9 marked "Applied For"; withholding applies until the TIN is furnished. The IRS General Instructions for Certain Information Returns say it plainly: if you do not collect and pay over backup withholding as required, you may become liable for any uncollected amount. That amount goes on Form 945.
Then the 1099-NEC itself. If the W-9 is still missing when you file, the return goes in without a correct TIN. For information returns due in 2027, Rev. Proc. 2025-32 sets the penalty at 340 per return under IRC 6721 and 340 per payee statement under IRC 6722. One contractor, two copies: 680. Corrected within 30 days, the tier drops to 60 per form.
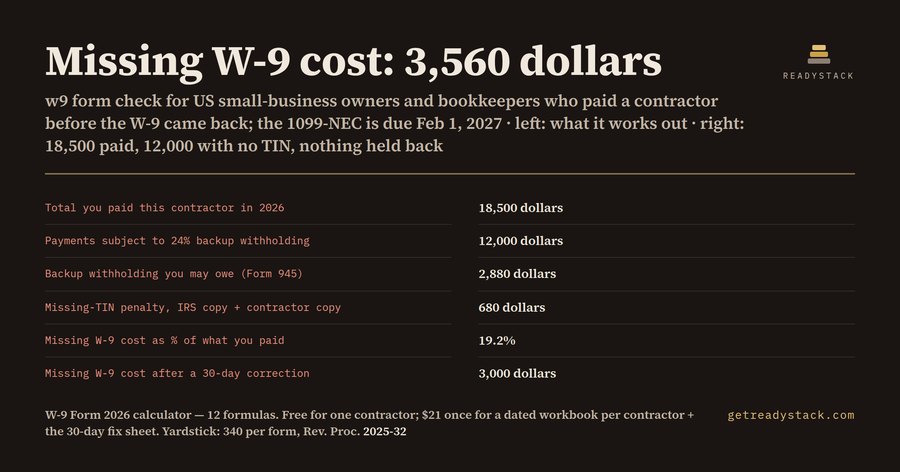
Here is the measured example the calculator opens with. You paid one contractor 18,500 in 2026. Of that, 12,000 went out after the year's total had reached 2,000, with no W-9 on file. You held nothing back, and you still have no signed W-9.
- Payments subject to 24% backup withholding: 12,000
- Backup withholding you may owe on Form 945: 2,880
- Missing-TIN penalty, IRS copy plus contractor copy: 680
- Missing W-9 cost: 3,560, which is 19.2% of what you paid
Change one fact and the answer changes. If the signed W-9 arrives before you file, the 680 penalty drops out and the cost is 2,880. If you did hold back 2,880, the cost is the 680 penalty alone. If the contractor's year stayed at 1,800, everything is zero and the page tells you there is 200 of room before the 2,000 mark.
The deadline: January 31, 2027 is a Sunday, so the 1099-NEC to the IRS and to the contractor and Form 945 for 2026 are due on Monday, February 1, 2027.
What to do today. Send the contractor a Form W-9 in writing. Until the signed form comes back, hold back 24% of every further payment; the workbook shows 240 for each additional 1,000 paid. Keep a record of when you asked.
The free page answers this in full for one contractor, with nothing hidden. The workbook is for keeping it: a dated .xlsx copy per contractor, with 8 inputs and 12 live formulas, and a second sheet that prices a correction within 30 days (120 instead of 680 in the example). It is a one-time payment, not a subscription.
15 seconds — what it actually does
Questions people ask
What does this W-9 form calculator work out?
For one contractor and tax year 2026 it says whether a 1099-NEC is required at the new 2,000 threshold, how much of what you paid without a W-9 falls under 24% backup withholding, what you may owe on Form 945, the 340-per-form missing-TIN penalty on both copies, and the total. The workbook holds 8 inputs and 12 formulas.
Who is it for?
Owners, office managers and bookkeepers of US small businesses that paid a freelancer, subcontractor, cleaner or consultant in 2026 before a signed Form W-9 came back. If that person's 2026 total reached 2,000 and you held nothing back, this is the number you need before the 1099-NEC and Form 945 are due on Feb 1, 2027.
Why not just use the free W-9 from irs.gov?
Send it today: the blank W-9 is how you stop the problem. But the form cannot tell you what you already owe for the payments made without it. Many 2026 guides also still quote the old 600 threshold, while OBBBA section 70433 moved both 1099-NEC reporting and backup withholding to 2,000 for payments made after Dec 31, 2025.
What is free and what is in the workbook?
The page gives the complete answer for one contractor, free, with nothing hidden: 1099-NEC duty, backup withholding owed, missing-TIN penalty and Missing W-9 cost. The workbook is for keeping and fixing it: a dated .xlsx copy per contractor for your records, plus a sheet pricing a corrected 1099-NEC filed within 30 days at 60 per form.
What does getting this wrong cost?
For information returns due in 2027, IRS Rev. Proc. 2025-32 sets 340 per return and 340 per payee statement, so one 1099-NEC still missing the TIN can cost 680. Uncollected backup withholding is 24% of what you paid without a TIN, and the IRS says the payer may become liable for it. The workbook is a one-time payment, not a subscription.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.