· ReadyStack
Worked example
Real numbers from this tool, line by line.
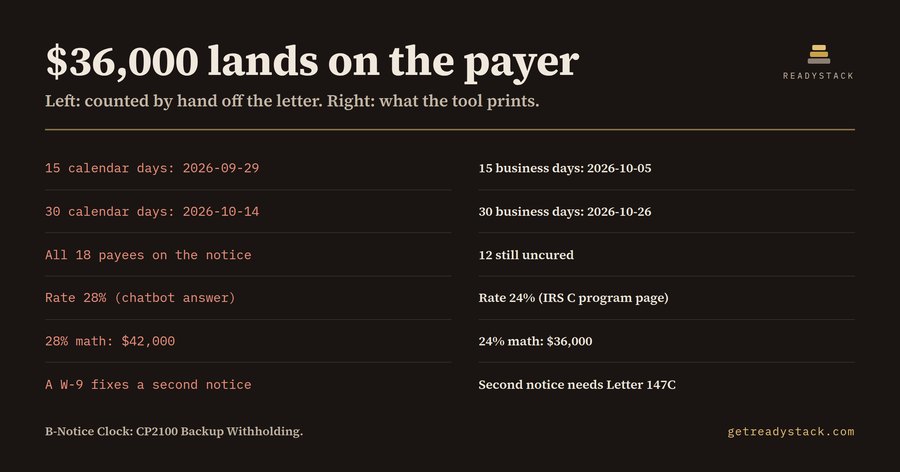
$36,000 is what an accounts-payable clerk at a US 1099 filer owes out of the company's own account when a CP2100 notice sits unworked for a month. Not the payee. The payer.
Here is how that number is built, because every piece of it is a date or a rate that is easy to get wrong.
The IRS sends a CP2100 or CP2100A when the taxpayer identification numbers on the Forms 1099 you filed do not match its records. The notice is not a bill. It is the start of two clocks, and the clocks run in business days.
The first clock is 15 business days: that is when the B-notice has to be in the mail to the payee. The second is 30 business days: that is when backup withholding has to start on every payee who has not cured the mismatch. Take a notice dated 2026-09-14. Fifteen calendar days lands on 2026-09-29, which is the answer a generic date calculator gives you, and it is wrong. Fifteen business days lands on 2026-10-05. Thirty calendar days lands on 2026-10-14; thirty business days lands on 2026-10-26. That is a three-week gap between the answer you get by counting squares on a wall calendar and the answer the statute asks for.
Then there is the rate, and this is the part where asking an AI assistant actively hurts you. Backup withholding under IRC section 3406 was reduced to 24 percent, scheduled to step back up to 28 percent, and a great deal of guidance written during that window still carries 28 percent. The IRS backup withholding C program page states 24 percent. A model trained across both eras will hand you either number with the same confidence. So this tool does not pick for you: the rate is a dropdown. Set it to 24 and eighteen payees minus six who returned a W-9 leaves twelve uncured, twelve at $12,500 of reportable payments is $150,000, and 24 percent of that is $36,000. Flip the dropdown to 28 and the same payee list produces $42,000. The $6,000 between those two figures is the cost of trusting a chatbot on a rate.
The last trap is the cure. A first B-notice is cured by a signed Form W-9 with a certified TIN. A second B-notice, for the same payee within three calendar years, is not - a W-9 does nothing. That payee has to send a Social Security card copy from SSA or a Letter 147C from the IRS. Switch the tool from "first" to "second" with nobody cured and the same eighteen payees carry $54,000, with a line on screen telling you a W-9 will not close it.
That is the whole free tool: one date, a payee count, a payment figure, a rate, and you get both statutory dates, the uncured count, the payer's dollar liability and the cure rule. No key, no cap, no watermark, and it runs in the browser so no payee data leaves the machine.
The paid key at $60 is a different axis, not a bigger version of the same thing. It exports the per-payee register as a CSV file you keep, and it sets browser alarms on both dates so the next notice does not depend on anyone remembering. Ownership and repetition, not access.
Source: timing from IRS Publication 1281; rate from the IRS Backup Withholding C Program page, checked 2026-09-22.
15 seconds — what it actually does
Full walk-through
Questions people ask
What does this extension actually do?
You type the date on your IRS CP2100 or CP2100A notice, how many payees it lists, and what you pay them. It returns the calendar date the B-notice must be mailed, the date backup withholding must begin, how many payees are still uncured, and the dollar liability you carry if you miss it.
Who is this for?
US accounts-payable clerks, payroll administrators and information-reporting staff at companies that file Forms 1099. It is written for the person who just opened a CP2100 envelope, has a payee list in front of them, and needs to know which day the mailing is due and what the exposure is.
Why not just ask a chatbot or use a free date calculator?
A free date calculator counts calendar days, not business days, and knows nothing about which day to count from. A chatbot will often quote 28 percent for backup withholding, the pre-sunset figure from older guidance. The IRS backup withholding C program page states 24 percent. Here the rate is a field you set, so the disagreement is visible instead of buried.
What is free and what needs the paid key?
Every calculation is free and unlimited: both dates, the uncured payee count, the dollar liability, and the cure rule for first versus second notices. There is no watermark and no usage cap. The 60 dollar key adds two different things: exporting the per-payee register as a CSV file you keep, and setting browser alarms on both deadlines.
What would this cost if a person did it?
The comparison that matters is not a fee, it is the liability. Under IRC section 3406 the payer, not the payee, owes every dollar it failed to withhold. On the worked example shipped with this tool, twelve uncured payees at 12,500 dollars each at 24 percent is 36,000 dollars the payer pays from its own account, plus the interest that rides on it.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.