· ReadyStack
Worked example
Real numbers from this tool, line by line.
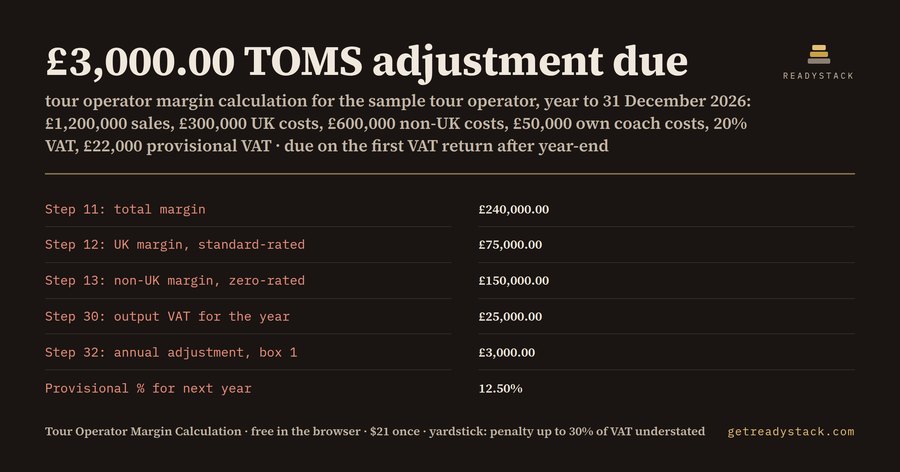
A UK tour operator with £1,200,000 of package sales in the year to 31 December 2026 owes £25,000.00 of output VAT under the Tour Operators' Margin Scheme. Having paid £22,000 provisionally, it still owes a £3,000.00 annual adjustment in box 1. That is the whole result of the year-end calculation in HMRC VAT Notice 709/5, section 9, on one sample business:
| Section 9 step | Sample tour operator |
|---|---|
| Step 1: package sales, VAT-inclusive | £1,200,000 |
| Step 2: bought-in costs enjoyed in the UK | £300,000 |
| Step 3: bought-in costs enjoyed outside the UK | £600,000 |
| Step 4: own UK coach costs £50,000 plus 20% VAT | £60,000.00 |
| Step 11: total margin | £240,000.00 |
| Step 12: UK margin, standard-rated | £75,000.00 |
| Step 13: non-UK margin, zero-rated | £150,000.00 |
| Step 30: output VAT for the year | £25,000.00 |
| Step 32: annual adjustment, box 1 | £3,000.00 |
| Step 29: VAT-exclusive value, box 6 | £275,000.00 |
Where the margin goes
The total margin is £1,200,000 less £960,000.00 of direct costs: £240,000.00. Section 9 does not split that margin by where the sales were made. It splits it in proportion to direct costs. UK-enjoyed bought-in costs are £300,000 of £960,000, so the UK margin is £75,000.00. The outside-UK costs take £150,000.00, which is zero-rated under paragraph 4.8. The own coach takes £15,000.00.
Why it is 1/6, not 20%
Step 20 applies the VAT fraction to the UK margin, because the margin is VAT-inclusive. At 20% the fraction is 1/6. £75,000.00 gives £12,500.00. Step 21 adds the in-house supply: £60,000.00 of costs plus £15,000.00 of margin, times 1/6, is another £12,500.00. Total output VAT is £25,000.00. Charging 20% straight on the margin would give £30,000.00 and overpay £5,000.00.
When the adjustment is due
Paragraph 5.7 has the force of law. The calculation is done immediately after the financial year-end, and any adjustment goes on the VAT return for the first period ending after it. For a year to 31 December 2026 that is the return for the period ending in January, February or March 2027. A careless error in a VAT return can carry a penalty of up to 30% of the VAT understated under Finance Act 2007 Schedule 24.
Next year's provisional percentage
Section 10 turns this year's figures into the percentage used on every return next year. Standard-rated VAT-inclusive supplies are £60,000.00 + £75,000.00 + £15,000.00 = £150,000.00. Divided by £1,200,000 that is 12.50%. A VAT period with £300,000 of sales then carries £6,250.00 of provisional output VAT.
What changes the answer
Move the costs, and the answer moves. If £600,000 of the bought-in costs were enjoyed in the UK and £300,000 outside it, the UK margin becomes £150,000.00. Output VAT becomes £37,500.00 and the adjustment £15,500.00, with 18.75% as next year's provisional percentage. If £40,000 had been paid provisionally on the original figures, box 1 would show £2,500.00 back.
What has changed in 2026
From 2 January 2026, Budget 2025 took standalone taxi and private hire journeys out of TOMS. A private hire journey sold on its own is no longer a margin scheme supply, so those fares stay out of step 1.
Check your own figures
The free calculator runs every step above in your browser, with your ledger totals: 7 inputs and 12 results, nothing uploaded. The workbook holds the same 12 formulas as the dated working paper for the client file.
15 seconds — what it actually does
Questions people ask
What does this tour operator margin calculation do?
It runs the VAT Notice 709/5 section 9 year-end TOMS calculation for one financial year: total margin, the margin split by direct costs between UK-enjoyed, outside-UK and in-house supplies, output VAT at the 1/6 VAT fraction, the box 1 annual adjustment, the box 6 value and next year's provisional percentage.
Who is this TOMS calculator for?
UK accountants, VAT managers and bookkeepers of tour operators and travel agents who buy in hotels, flights, coaches or excursions and resell them as principal. It suits businesses with bought-in UK and outside-UK travel and standard-rated in-house supplies such as their own UK coach, using the cost-based method.
Why not use a free VAT calculator?
Free VAT calculators take 20% of the margin or split it by sales. Section 9 splits the total margin in proportion to direct costs and takes the VAT fraction, 1/6 at 20%. On the sample year that is £25,000.00, where 20% would say £30,000.00 and overpay £5,000.00. They also do not carry the provisional percentage into next year.
What is free and what does the $21 add?
The whole calculation is free in the browser: every step, the box 1 adjustment, the box 6 value and next year's provisional percentage for your own figures. The $21 one-time workbook is the same 12 live formulas in an .xlsx you keep per client and year, with the HMRC sources, as the working paper behind the return.
What does getting the TOMS adjustment wrong cost?
The adjustment belongs on the first VAT return ending after your financial year-end (paragraph 5.7). An understatement through carelessness can carry a penalty of up to 30% of the VAT understated under Finance Act 2007 Schedule 24, on top of the VAT and interest. The free check takes about two minutes with your ledger totals.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.