· ReadyStack
Worked example
Real numbers from this tool, line by line.
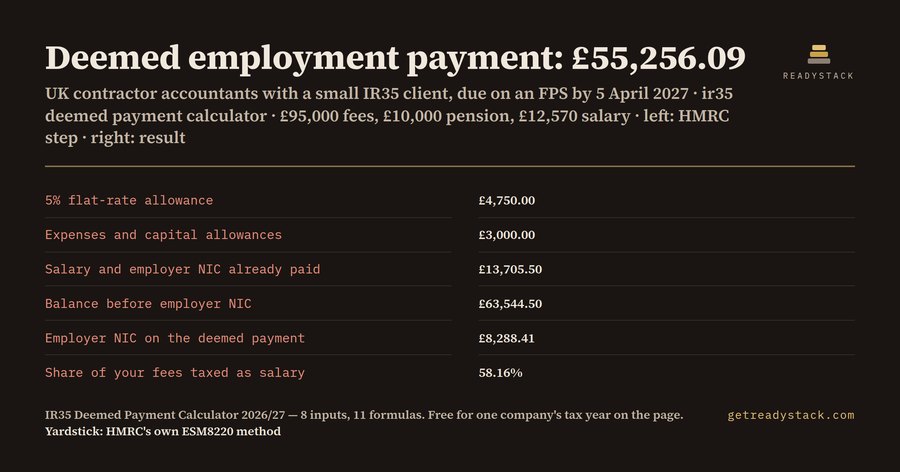
A UK contractor whose personal service company bills a small client £95,000 inside IR35 ends 2026/27 with a deemed employment payment of £55,256.09 and £8,288.41 of employer NIC on top, after the 5% allowance, £10,000 of employer pension and a £12,570 salary.
| Step | 2026/27 |
|---|---|
| Fees from inside-IR35 engagements | £95,000.00 |
| 5% flat-rate allowance | £4,750.00 |
| Income after the 5% and direct payments | £90,250.00 |
| Expenses and capital allowances | £3,000.00 |
| Employer pension contributions | £10,000.00 |
| Salary and employer NIC already paid | £13,705.50 |
| Balance before employer NIC | £63,544.50 |
| Deemed employment payment | £55,256.09 |
| Employer NIC on the deemed payment | £8,288.41 |
That is 58.16% of the fees taxed as salary. The figures come from the calculator on this page, which runs the same 11 formulas as the workbook.
Why your company does this sum, not the client
Under the off-payroll rules in Chapter 10 ITEPA 2003, a medium or large client decides status and its fee payer deducts PAYE. A small client does neither. If your client is small, the older Chapter 8 rules apply: your company decides whether the engagement is inside IR35 and, if it is, works out the deemed employment payment at the end of the tax year. GOV.UK says to report it on a Full Payment Submission on or before 5 April each year, so the next date is 5 April 2027.
More contractors will be doing it from 2027/28
HMRC updated ESM10006a on 7 October 2026. For financial years beginning on or after 6 April 2025, a company is medium or large only above £15 million turnover or a £7.5 million balance sheet (the 50-employee test did not change). The page says the earliest tax year this moves a client out of the client-led rules is 2027/28. A client that sat just above the old £10.2 million line can become small again, and from then your company runs the deemed payment calculation itself.
The steps, as HMRC sets them out
- Take the fees your company received for the engagements and deduct a flat 5%. You do not have to show what the 5% was spent on.
- Add any payments the client made to you directly.
- Deduct the expenses the company paid that an employee could claim, and capital allowances on equipment the work needs.
- Deduct employer pension contributions.
- Deduct the salary and benefits already paid to you and the employer NIC on them.
- If the balance is nil or negative, there is no deemed payment.
- Otherwise, take out the employer NIC on the deemed payment itself. HMRC's ESM8220 does this as balance × 100/(100+15) at the 15% rate.
In the example, £63,544.50 ÷ 1.15 = £55,256.09, and the £8,288.41 left over is the employer NIC.
Three cases that change the answer
- Fees fall to £60,000 and pension rises to £20,000: the deemed payment drops to £17,647.39.
- Fees of £20,000 against a £12,570 salary: the balance is nil, so there is no deemed payment.
- The £95,000 example above: £55,256.09.
What the free page does and what the workbook adds
The page gives the full answer for one company and one tax year, with every step shown. You type your own figures and see the result before you pay anything. The workbook is the working paper for the client file. It shows the year-end lines the page does not: employment income for the P60 (£67,826.09 in the example), employer NIC for the whole tax year (£9,423.91) and the Corporation Tax deduction for the deemed payment and its NIC (£63,544.50). It is a one-off payment, not a subscription.
15 seconds — what it actually does
Questions people ask
What does this IR35 deemed payment calculator work out?
It follows HMRC's steps for the Chapter 8 deemed employment payment: 5% flat allowance on your inside-IR35 fees, add payments the client made to you directly, deduct expenses, capital allowances, employer pension, salary and the employer NIC on it, then take out employer NIC at 100/115. With the example figures the deemed payment is £55,256.09.
Who needs to calculate a deemed employment payment?
A UK personal service company whose engagement falls inside IR35 for a small private-sector client. A small client does not make the status determination, so your company decides status, works out the deemed employment payment itself and reports it on a Full Payment Submission on or before 5 April. Contractor accountants run this for each such client.
Why not use a free IR35 calculator?
Most free IR35 calculators model the Chapter 10 rules, where a medium or large client's fee payer deducts PAYE from the invoice. A small client leaves you under Chapter 8, which needs the 5% allowance, the pension, salary and expense deductions and the 100/115 employer NIC step. Those Chapter 8 steps are what this calculator applies.
What is free and what do I get in the full version?
Free: the whole deemed employment payment for one company and one tax year on this page, every step shown, as often as you like. Full version: the .xlsx working paper for the client file, with P60 employment income including the deemed payment, total employer NIC for the year and the Corporation Tax deduction line, kept as one dated copy per company.
What does a wrong deemed payment cost?
The deemed payment is taxed as salary, with employer NIC at 15% on top. In the example, £95,000 of fees produce a £55,256.09 deemed payment and £8,288.41 of employer NIC. If the FPS misses 5 April, PAYE is late. HMRC's provisional-figure concession still charges interest on the balancing payment, though it waives the late payment penalty.
When do the small client rules change next?
HMRC's ESM10006a (updated 7 October 2026) says the higher Companies Act thresholds of £15 million turnover and £7.5 million balance sheet apply to financial years beginning on or after 6 April 2025. The earliest tax year in which that moves a client out of the client-led rules is 2027/28, which starts 6 April 2027. From then, your company runs the deemed payment calculation itself.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.