· ReadyStack
Worked example
Real numbers from this tool, line by line.
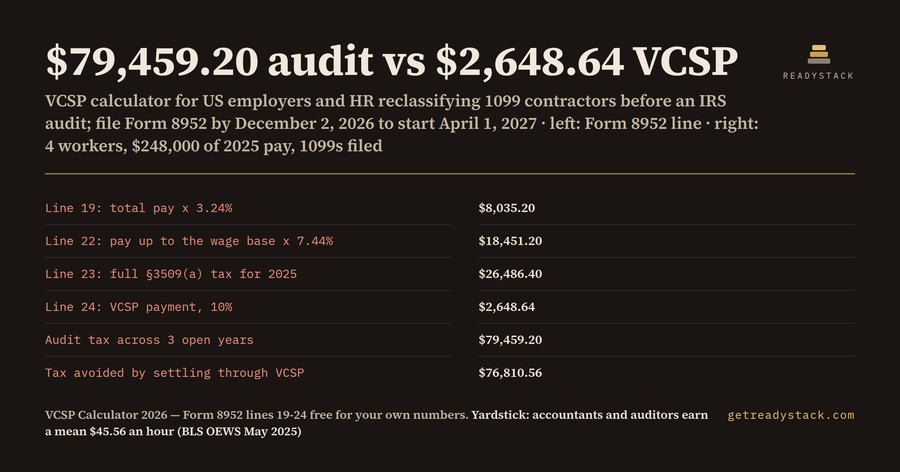
$79,459.20 is the employment tax an IRS audit would assess over 3 open years on an employer who paid 4 workers $248,000 on Forms 1099 in 2025, and $2,648.64 is what the same employer pays to settle through the Voluntary Classification Settlement Program (VCSP) on Form 8952.
| Form 8952 Part IV | Amount |
|---|---|
| Line 18: total 2025 pay | $248,000.00 |
| Line 19: line 18 x 3.24% | $8,035.20 |
| Line 21: pay up to the wage base | $248,000.00 |
| Line 22: line 21 x 7.44% | $18,451.20 |
| Line 23: full §3509(a) tax for 2025 | $26,486.40 |
| Line 24: VCSP payment, 10% | $2,648.64 |
| Audit tax, 3 open years, before interest and penalties | $79,459.20 |
If you run payroll or HR for a US business and you have contractors who look like employees, this is the decision in one table. VCSP charges 10% of one year's tax, with no interest or penalties, and the IRS will not audit earlier years on those workers' classification. An audit charges the full amount for each year it can still reach, then adds interest and penalties on top.
Where 3.24% and 7.44% come from
IRC §3509(a) lets an employer who misclassified a worker pay income tax withholding at 1.5% of wages and the employee's FICA at 20% of the normal amount, plus the employer's own FICA in full. Form 8952 folds that into two rates. Line 19 is 1.5% withholding plus 1.45% employer Medicare plus 20% of the employee's 1.45%: 3.24% of all pay. Line 22 is 6.2% employer social security plus 20% of the employee's 6.2%: 7.44% of pay up to the wage base.
The wage base trap
The wage base is applied per worker, and it is the base for the year the pay was made. A Form 8952 filed in 2026 looks at 2025 pay, so the cap is $176,100, not the 2026 figure of $184,500. One worker paid $200,000 in 2025 has $23,900 above the cap on line 20. That gives line 23 of $19,581.84 and a VCSP payment of $1,958.18, against $58,745.52 of audit tax over 3 years.
The 1099 trap
VCSP is only open if you filed every required Form 1099 for these workers for the 3 preceding years. Miss them and §3509(b) doubles the reduced rates to 3% withholding and 40% of the employee FICA. Six workers paid $300,000 with no 1099s: VCSP is closed, and the audit tax is $41,130.00 a year, $123,390.00 over 3 years, before interest and penalties.
The 120-day date
The IRS asks for Form 8952 at least 120 days before the first day you treat the workers as employees. To start on April 1, 2027, file by December 2, 2026. The workbook works out the date for any start you pick.
What is free and what is in the file
The calculator on the page runs every line above for your own numbers, in your browser, with nothing blocked. The paid .xlsx is for filing: a 50-row worker roster that applies the $176,100 wage base per worker and fills line 20, the 8 Form 8952 Part V eligibility representations as a yes/no checklist, and the 120-day filing-date sheet. It covers federal income tax withholding and FICA only; FUTA and state taxes are outside the Form 8952 payment. Have a CPA or enrolled agent review the filing.
15 seconds — what it actually does
Questions people ask
What does this VCSP calculator work out?
It fills Form 8952 Part IV for you: line 19 (pay x 3.24%), line 22 (pay up to the wage base x 7.44%), line 23 and the line 24 VCSP payment of 10%. Example: 4 workers paid $248,000 in 2025 gives line 23 $26,486.40 and a VCSP payment of $2,648.64, against $79,459.20 of audit tax over 3 open years.
Who is this calculator for?
US business owners, HR and payroll managers who paid workers on 1099s, now think they are employees, and want to fix it before the IRS does. It suits anyone who must decide in 2026 whether to file Form 8952 or wait, and who needs the dollar figure for that decision before talking to a CPA.
Why not ask a chatbot or use a free payroll calculator?
General tools miss the form's own rules. Form 8952 folds IRC §3509(a) into 3.24% and 7.44%. A 2026 filing looks at 2025 pay, so the wage base on line 20 is $176,100, not $184,500. If 1099s were not filed for the three prior years, §3509(b) doubles the rates to 3% and 40% and VCSP is closed.
What is free and what does the paid file add?
Free: the whole Part IV calculation and audit comparison for your numbers in the browser, with no limits. The $21 Excel workbook adds what you need to file: a 50-row worker roster that applies the $176,100 wage base per worker and fills line 20, the 8 Part V eligibility representations as a checklist, and a 120-day filing-date sheet.
What does getting this wrong cost?
Under VCSP you pay 10% of one year's §3509(a) tax and no interest or penalties, and the IRS will not audit prior years for those workers' classification. In an audit the full §3509 tax is assessed for each open year, plus interest and penalties. In the example that is $2,648.64 against $79,459.20 before interest and penalties.
When do the numbers change next?
On January 1, 2027. A Form 8952 filed in 2027 looks at 2026 pay, and the IRS instructions (Rev. 11-2025) set the 2026 social security wage base at $184,500, so line 20 changes. The 120-day rule also moves your file-by date: to start treating workers as employees on April 1, 2027, file by December 2, 2026.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.