· ReadyStack
Worked example
Real numbers from this tool, line by line.
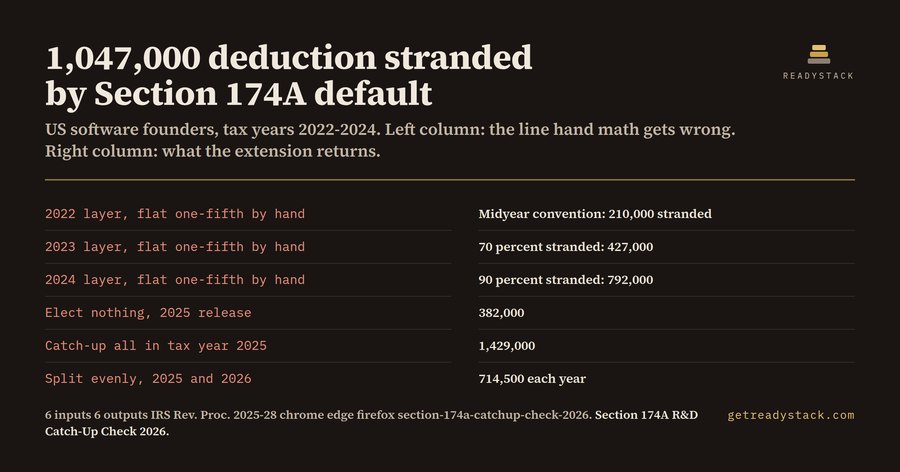
A US software founder with 420,000, 610,000 and 880,000 of domestic research spend across tax years 2022, 2023 and 2024 is sitting on 1,429,000 of deduction that was never taken -- and 1,047,000 of it stays off the 2025 return unless somebody makes an election before the year closes.
Here is where the hand estimate goes wrong. The TCJA rule that took effect for tax years beginning after 2021-12-31 made domestic research expenditures amortizable over five years, and it did so on a midyear convention. The year you spend the money you deduct 10 percent. The next four years take 20 percent each. The tail 10 percent lands in year six. Divide by five instead and the 2022 layer looks 60 percent deducted when it is 50 percent: 10 plus 20 plus 20. The 2023 layer is 30 percent deducted, not 40; the 2024 layer 10 percent, not 20.
Run that on the three numbers above. The 2022 layer leaves 210,000 stranded. The 2023 layer leaves 427,000. The 2024 layer leaves 792,000. Total: 1,429,000 sitting on the balance sheet on 2025-01-01, already spent, not yet deducted.
OBBBA, signed in July 2025, added Section 174A and restored immediate deduction of domestic research expenditures for tax years beginning after 2024-12-31. Rev. Proc. 2025-28 set out how the stranded balance comes home: deduct it entirely in that first year, or ratably across 2025 and 2026, either way as a Section 481(a) method change. Do nothing and the old schedule grinds on -- 382,000 in 2025 and 382,000 in 2026.
So the three routes on one screen look like this. Elect nothing: 382,000 in 2025. Take the catch-up all in 2025: 1,429,000, which is 1,047,000 more than the do-nothing baseline and worth 300,090 in tax cash at a 21 percent rate. Split it: 714,500 in 2025 and 714,500 in 2026, worth 150,045 of 2025 cash. Which one wins is a rate question and a Section 163(j) question, since Rev. Proc. 2025-28 counts the released amount as amortization for the business interest limitation.
There is a second door, on a timer. A small business meeting the Section 448(c) test -- average gross receipts not above 31,000,000, tested for 2025 -- may elect Section 174A retroactively for 2022, 2023 and 2024 on amended returns or AARs. The deadline is the earlier of 2026-07-06 or that year's Section 6511 refund window, and for most 2022 calendar-year returns the refund statute closes first. Cross 31,000,000 and that door was never open; the 2025 catch-up is the only route.
Why not just ask a chatbot? Most models were trained while capitalization was the law, so they recite the five-year rule OBBBA replaced, apply a flat fifth, and never mention 2026-07-06.
What it costs to be late is a published number. If the automatic window closes and you have to ask the IRS for relief to make a late election under Treas. Reg. 301.9100-3, the user fee alone is $13,900 for requests received after 2025-02-01, before a single hour of professional time. The automatic route under Rev. Proc. 2025-28 has no user fee at all. The expensive part is never the filing. It is the date.
The extension is a browser popup with six inputs and six outputs. Type your three spend figures, your rate and your gross receipts, pick a route, and these numbers appear for your file instead of the example. All of it is free and unlimited, with no key and no locked result. A $60 licence adds keeping rather than knowing: a CSV of every input and all three routes for your preparer, and alarms before 2026-07-06. Your figures never leave the browser.
Questions people ask
What does the Section 174A R&D Catch-Up Check actually do?
It takes your domestic research spend for tax years 2022, 2023 and 2024 and computes how much of it is still unamortized on 2025-01-01 under the TCJA five-year schedule with the midyear convention. It then shows what Section 174A releases if you deduct the balance all in 2025, split it across 2025 and 2026, or elect nothing at all.
Who is this built for?
US software, hardware and engineering companies that capitalized research costs on their 2022, 2023 and 2024 federal returns, and the bookkeepers and controllers preparing those clients' 2025 and 2026 filings. It is aimed at the firm small enough that nobody has run a formal method-change study but large enough that the stranded balance is six or seven figures.
Why will a chatbot or a generic tax calculator not answer this?
Most models were trained while Section 174 capitalization was the law and still answer with the five-year amortization rule that OBBBA replaced in July 2025. They also apply a flat one-fifth per year and miss the midyear convention, which is why a hand estimate of the 2022 layer comes out at forty percent instead of fifty percent unamortized.
What is free and what does the key unlock?
Every calculation is free, unlimited, with no key, no watermark and no locked result: the stranded balance, both catch-up routes, the do-nothing baseline, the cash value and the gross-receipts verdict. The 60 dollar key adds a different axis entirely, ownership and repetition: CSV export of the workpaper, and repeating alarms before the 2026-07-06 deadline.
What would this cost handled the other way?
If the automatic window closes and you have to ask the IRS for late-election relief under Treasury Regulation 301.9100-3, the user fee alone is 13,900 dollars for requests received after 2025-02-01, before any CPA time. The automatic route under Rev. Proc. 2025-28 carries no IRS user fee, which is exactly why the date matters more than the fee.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.