· ReadyStack
Worked example
Real numbers from this tool, line by line.
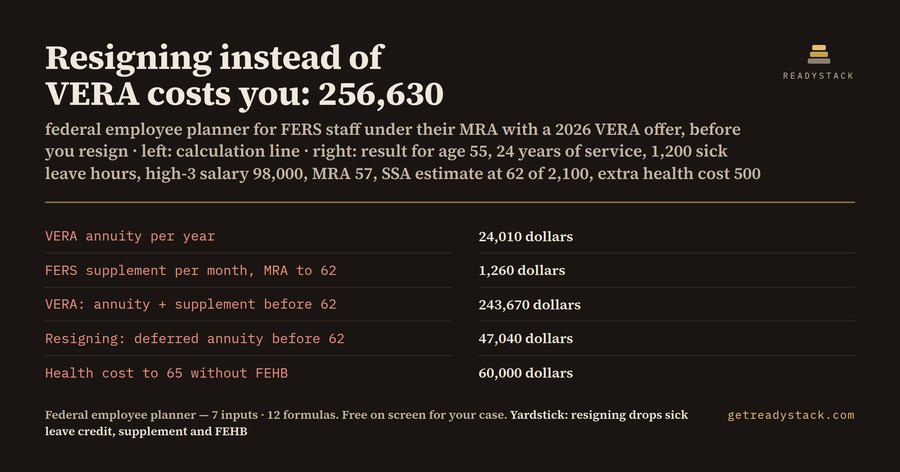
A FERS employee aged 55 with 24 years of service who resigns instead of taking VERA gives up 256,630 dollars by age 62 in this worked example. VERA pays 243,670 dollars before 62. Resigning before the MRA pays 47,040 dollars before 62, and replacing FEHB costs 60,000 dollars to 65.
| Line | Result |
|---|---|
| VERA annuity per year (1% x high-3 x service) | 24,010 dollars |
| FERS supplement per month, from MRA to 62 | 1,260 dollars |
| VERA: annuity + supplement paid before 62 | 243,670 dollars |
| Resigning: deferred annuity per year (no sick leave credit) | 23,520 dollars |
| Resigning: deferred annuity paid before 62 | 47,040 dollars |
| Resigning: health cost to 65 without FEHB | 60,000 dollars |
The inputs: age 55 on the separation date, 24 years of creditable service, 1,200 hours of unused sick leave, a high-3 average salary of 98,000, an MRA of 57 (born 1970 or later), a Social Security estimate at 62 of 2,100 a month, and 500 a month of extra health cost without FEHB.
Three things disappear at once
VERA is an immediate annuity. Resigning before your minimum retirement age is not, and three rules follow from that.
First, sick leave. Under 5 U.S.C. 8415(m), 100% of unused sick leave is added to your service when you retire on an immediate annuity. 1,200 hours at a 2,087-hour work year bring 24 years to 294 whole months, so the VERA annuity is 1% x 98,000 x 294 / 12 = 24,010 a year. The deferred annuity after a resignation uses the 24 years alone: 23,520 a year.
Second, the FERS supplement. On VERA it starts at your MRA and stops at 62. It is your Social Security estimate at 62 times your FERS years over 40 (5 CFR 842.504): 2,100 x 24 / 40 = 1,260 a month, paid for 5 years in the example. A deferred annuity carries no supplement.
Third, health insurance. To keep FEHB in retirement you must retire on an immediate annuity and have been enrolled for the 5 years before it starts. A deferred annuity has no FEHB and no FEGLI, and you cannot re-enroll later.
When a deferred annuity starts
If you resign with 24 years before your MRA, the deferred annuity starts unreduced at 60 (20 years of service) or at 62. With 30 years it starts unreduced at your MRA. With 10 to 29 years you can start it at your MRA, but it is cut by 5/12 of 1% for each month under 62 (5 U.S.C. 8413, 8415(h)). In the example that is 23,520 x 0.75 = 17,640 a year for life, which is on the second sheet of the workbook.
The math, line by line
VERA before 62: 24,010 x 7 years + 1,260 x 12 x 5 years = 243,670. Resigning: 23,520 x 2 years (60 to 62) = 47,040. Health: 500 x 12 x 10 years = 60,000. Gap: 243,670 - 47,040 + 60,000 = 256,630.
No COLA is paid before 62 to a regular FERS retiree, so these figures do not grow before 62 on either path.
What the calculator does not cover
It assumes FERS-only service, a separation before your MRA and no special retirement provisions. It does not add VSIP, which is at most 25,000 dollars and can come with either path. The supplement is cut by the earnings test if you earn above the Social Security exempt amount (5 U.S.C. 8421a). If you are already past your MRA, an MRA+10 retirement keeps FEHB, so the comparison changes.
Next step
Put your own numbers in the free calculator, then ask HR for an official annuity estimate under VERA with your sick leave balance, and confirm your 5 years of FEHB coverage before you sign anything. Not legal or financial advice; OPM decides your annuity.
15 seconds — what it actually does
Full walk-through
Questions people ask
What does this FERS annuity calculator compare?
It sets a VERA early retirement against resigning before your MRA. VERA pays an immediate annuity of 1% of high-3 per year of service, with unused sick leave added, and a FERS supplement from your MRA to 62. Resigning gives a deferred annuity without sick leave credit, no supplement and no FEHB. The last line is the gap by 62, plus health cost to 65.
Who is this federal employee planner for?
FERS employees who are under their MRA, hold a 2026 VERA offer and are weighing it against resigning or a deferred resignation. It assumes FERS-only service, no special retirement provisions (law enforcement, firefighter, air traffic) and no CSRS component. If you are already past your MRA, an MRA+10 retirement keeps FEHB, so ask HR instead.
Why not use a free FERS retirement calculator?
Free calculators price one pension at a time. They do not show that resigning before your MRA drops three things at once: the unused sick leave credit (5 U.S.C. 8415(m) credits it only on an immediate annuity), the FERS supplement and FEHB in retirement. This page puts both paths side by side with your own numbers.
What is free and what does the full version add?
Free: the whole comparison for your case on screen, as often as you like, with no account. The full version is the workbook you keep and rerun at every new offer, with a second sheet for the reduced annuity you could start at your MRA and the months you wait for the supplement, a 14-line VERA checklist with a source per line, and the offline page.
What does it cost compared with the alternatives?
One payment, not a subscription, and you see your own answer before you pay. The alternative is an annuity estimate from your HR office, which is free but often slow during a realignment, or a federal-benefits planner. Use this to know your gap before you ask HR, then let the official estimate confirm it.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.