· ReadyStack
Worked example
Real numbers from this tool, line by line.
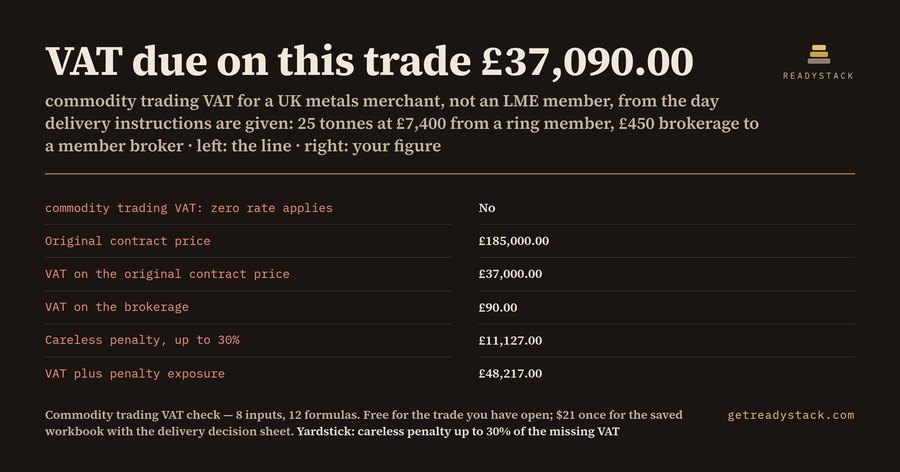
VAT due on this trade: £37,090.00, for a UK metals merchant who is not a market member and took delivery of 25 tonnes bought at £7,400 a tonne from an LME ring-dealing member.
| Line | Value |
|---|---|
| Original contract price | £185,000.00 |
| Terminal market zero rate applies | No |
| VAT on the original contract price | £37,000.00 |
| VAT on the brokerage (£450) | £90.00 |
| VAT due on this trade | £37,090.00 |
| Careless penalty, up to 30% | £11,127.00 |
| VAT plus penalty exposure | £48,217.00 |
Close the same contract out before any delivery instruction and the VAT is £0.00. The delivery instruction alone added £37,090.00.
Why the answer flips
VAT Notice 701/9 zero-rates futures in commodities ordinarily dealt with on a listed terminal market when the trade is between two market members, or between a member and a non-member as long as it does not lead to physical delivery. Delivery takes place when instructions are given for the goods to be physically removed from the warehouse or vault. From that moment the notice says VAT must be accounted for on the basis of the original contract price, not on a net settlement figure.
Most of the time a non-member closes out and never sees a VAT line. The trade that goes to delivery is the one that gets missed, because the books treated every exchange trade the same way.
The broker's commission follows the trade
A member broker who arranges a zero-rated trade can zero-rate the brokerage. When the trade it arranges is not zero-rated, the brokerage is standard-rated, and VAT is due on the whole commission, with no deduction for any part paid on to third parties. A broker that is not a member of a listed market cannot use the terminal market zero rate at all. An introducer who receives a share of the broker's commission makes a standard-rated supply unless the conditions in paragraph 3.2.5 are met.
Goods that are zero-rated anyway
If the goods themselves are zero-rated, for example most food, a delivered contract between a member and a non-member still carries no VAT on the goods. Metals and oil are not in that group, so the full 20% applies.
What a mistake costs
Under Finance Act 2007 Schedule 24, a careless inaccuracy in a VAT return can cost up to 30% of the VAT that was missing. If HMRC finds it first, the lowest the penalty can go is 15%. If you tell HMRC before they ask, it can go down to 0%. On the example trade, the gap between those two is up to £11,127.00.
Three trades, three answers
- Member to member, delivered and registered with the clearing house: zero-rated, £0.00 VAT.
- Member to non-member, closed out before delivery: zero-rated, £0.00 VAT, and the member broker's commission is zero-rated too.
- Member to non-member, delivery instructed, metals: £37,000.00 VAT on the goods plus £90.00 on the brokerage.
Check your own trade
Enter your tonnes, your original contract price per tonne, who is a market member, whether delivery instructions were given and your brokerage. The page shows the zero rate test, the VAT due and the penalty exposure straight away, free and with no limit on runs. The full version is the Excel workbook with the delivery decision sheet, saved once per trade as the record behind your VAT return.
15 seconds — what it actually does
Full walk-through
Questions people ask
What does this calculator check?
It applies the terminal market zero rate of VAT Notice 701/9 to one trade: whether seller and buyer are listed market members, whether delivery instructions were given, whether the goods are zero-rated anyway, and whether your broker is a member. It then gives the VAT due on the original contract price and brokerage, and the careless penalty of up to 30%.
Who is this for?
VAT-registered metals merchants, commodity trade houses, small brokers and introducing brokers in the UK who trade LME or ICE contracts with a listed market member, and the bookkeepers who file their VAT returns. It is for anyone who has assumed every exchange trade is zero-rated and now has a contract that went to delivery.
Why not just read HMRC's notice or ask a chatbot?
Notice 701/9 states the rules in prose and still lists old market names. It does not apply the member, delivery and broker tests to your trade or put a pound figure on them. Commodity futures are also not VAT-exempt financial services: on a listed market they are zero-rated, and off it they follow the goods.
What is free?
The whole check on the page is free with no limit on runs: 8 inputs and 10 formulas giving the contract price, the member test, whether the zero rate applies, the VAT on the contract, the VAT on the brokerage, the VAT due, the careless penalty of up to 30% and your total exposure. Your figures stay in your browser.
What does the paid version add?
A saved Excel workbook with 8 inputs and 12 formulas: the same 10 lines plus a delivery decision sheet showing the VAT if the contract is closed out with no delivery and the VAT the delivery instruction adds. Keep one dated copy per trade for your accountant or an HMRC check. It is a one-time payment, not a subscription.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.