· ReadyStack
Worked example
Real numbers from this tool, line by line.
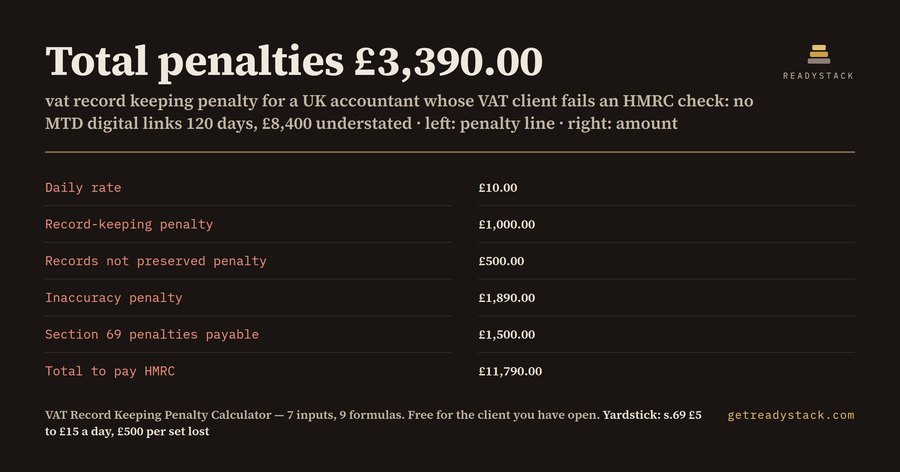
Total penalties £3,390.00: that is what a UK accountant's VAT client faces when it kept no MTD digital links for 120 days, had 1 earlier failure, lost 1 set of records and HMRC found £8,400 of VAT understated.
| Line | Result |
|---|---|
| Daily rate | £10.00 |
| Days counted (max 100) | 100 |
| Record-keeping penalty | £1,000.00 |
| Records not preserved penalty | £500.00 |
| Schedule 24 penalty % | 22.5% |
| Inaccuracy penalty | £1,890.00 |
| Section 69 penalties payable | £1,500.00 |
| Total to pay HMRC | £11,790.00 |
The total to pay HMRC is the £8,400 of VAT plus £3,390.00 of penalties, before late payment interest.
Where each line comes from
The daily rate is VATA 1994 s.69(3). It is £5 if the client had no earlier failure of the same requirement in the 2 years before this one began, £10 after one earlier failure, and £15 after two or more. Section 69(1) multiplies that rate by the days the failure continues, up to a maximum of 100 days, and the penalty is never less than £50. A client with 120 days of copy-and-paste spreadsheets and one earlier failure therefore pays £10 × 100 = £1,000.00.
The preservation penalty is s.69(2): £500 for failing to preserve records that HMRC required to be kept. VAT Notice 700/21 para 2.4 says VAT records must generally be kept for at least 6 years. One lost set of purchase invoices is £500.00.
The inaccuracy penalty is Finance Act 2007 Schedule 24. When HMRC finds the error (a prompted disclosure), a careless error carries a maximum of 30% and a minimum of 15% of the VAT understated. Where the penalty lands between the two depends on the quality of the disclosure: telling HMRC, helping them and giving access to the records. At 50% disclosure quality the rate is 22.5%, so £8,400 × 22.5% = £1,890.00.
The rule most estimates miss: s.69(9)
Section 69(9) says that conduct which is penalised under Schedule 24 does not also give rise to a section 69 penalty. If the only failure is the one that caused the wrong return, the client pays the Schedule 24 penalty and the s.69 lines fall to zero: the total penalties drop from £3,390.00 to £1,890.00. If the record failure is a separate failing (for example missing digital links on top of an unrelated error), both apply. The calculator has one 1/0 input for exactly this.
Three situations that change the answer
- Careless error, separate record failure (the example above): total penalties £3,390.00.
- The same conduct caused both: total penalties £1,890.00.
- HMRC says deliberate and concealed, first failure, full help with the check: the rate is 50% (the prompted minimum), the inaccuracy penalty £4,200.00, and total penalties £5,200.00.
What the free page does and what the workbook adds
The free page takes 7 inputs and runs 9 formulas, from the daily rate to the total to pay HMRC. It runs in your browser and nothing is uploaded. The workbook (7 inputs · 12 formulas) has the same lines as live Excel formulas and a second sheet that prices the same VAT if HMRC calls it deliberate (35% prompted minimum) or deliberate and concealed (50%). You keep one dated copy per client and per check.
Before you reply to the HMRC officer
Check whether a reasonable excuse applies (s.69(8)). Write down the help you are giving, because that is what moves the Schedule 24 rate from 30% towards 15%. Late payment interest is charged on top at HMRC's rate, which is 7.75% from 9 January 2026.
15 seconds — what it actually does
Questions people ask
What does this VAT record keeping penalty calculator work out?
It prices a VAT record-keeping failure the way the law does: the s.69 daily penalty of £5, £10 or £15 for up to 100 days with a £50 minimum, £500 for each set of records not preserved, the Schedule 24 inaccuracy penalty on the VAT understated after your disclosure reduction, and the s.69(9) rule that stops both penalties for the same conduct.
Who is it for?
UK accountants, bookkeepers and finance managers whose VAT-registered client or company is in an HMRC check and cannot show Making Tax Digital digital records, digital links or 6 years of records. You type the client's own facts and get a figure you can put in the client letter.
Why not just read the HMRC notice?
VAT Notice 700/21 and 700/22 say which records to keep but never give a pound figure for a failure. The day rate, the 100-day cap, the £50 minimum, the s.69(9) offset and the Schedule 24 reduction for disclosure sit in different parts of VATA 1994 and FA 2007.
What is free?
The whole calculation on the page: 7 inputs and 9 formulas, from the daily rate to the total to pay HMRC, with no sign-up and no limit on how often you use it. The paid part is the Excel workbook with a second sheet for deliberate and concealed behaviour that you save per client and per check.
What does a wrong figure cost?
A careless error HMRC finds carries up to 30% of the VAT understated; a deliberate one up to 70%, and deliberate and concealed up to 100%. On the example of £8,400 understated, the gap between a 22.5% careless penalty and a 50% concealed minimum is £2,310 of the client's money.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.