· ReadyStack
Worked example
Real numbers from this tool, line by line.
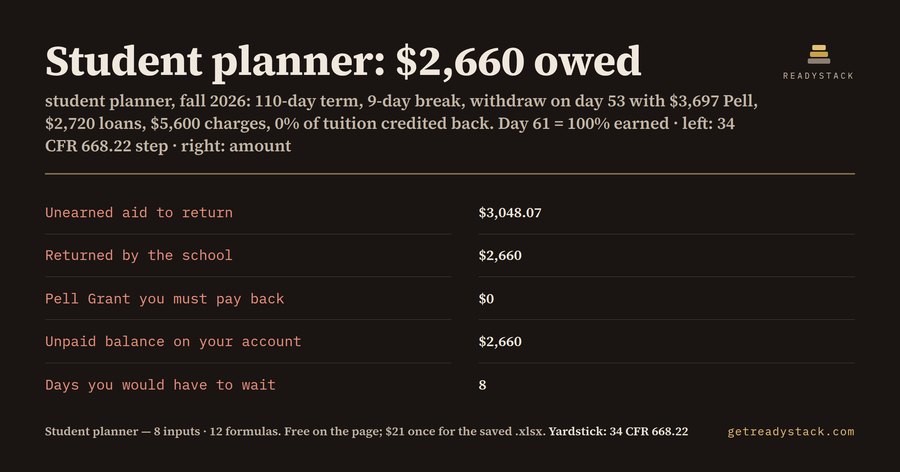
A US college student on a Pell Grant who withdraws from every class on day 53 of a 110-day fall 2026 term leaves a $2,660 unpaid balance on the school account; waiting until day 61 leaves $0. Here is the worked case, computed by the calculator on this page:
| Step under 34 CFR 668.22 | Amount |
|---|---|
| Term days, 9-day Thanksgiving break removed | 101 |
| Share of the term completed (53 of 101) | 0.525 |
| Aid earned, of $3,697 Pell + $2,720 Direct Loans | $3,368.93 |
| Unearned aid to return | $3,048.07 |
| Returned by the school (lesser of unearned aid or $5,600 charges x 0.475) | $2,660 |
| Your share that is loans, repaid on normal loan terms | $60 |
| Pell Grant you must pay back after the 50% protection | $0 |
| Unpaid balance left on your school account, 0% tuition refund | $2,660 |
| Term day when 100% of aid is earned | 61 |
Why day 61 and not day 66
The federal Return of Title IV Funds rule counts calendar days, not class days. Scheduled breaks of at least five consecutive days are taken out of both the term total and the days you completed. A plain count says 60% of 110 days is day 66. With the 9-day break removed, the term is 101 days, and you pass 60% on day 61 (0.604). On day 60 you are at 0.594, so the rule still prorates your aid. If the break falls before the day you leave, you subtract its days from the days you completed too, which pushes the date later.
Who pays what
The school returns first: the lesser of the unearned aid or its charges for the term times the unearned share. In the example that is $2,660. It goes back to the loans first, then to the Pell Grant. The money came off your bill when the aid was paid out, so once it goes back, the charges are uncovered again. Whether you owe all of it depends on your school's own tuition refund policy, which is a separate input. The example uses 0%: a school whose refund period has already ended.
What is left is your share. The loan part ($60 here) you simply repay on the normal terms of the loan. The grant part has a protection: you do not have to return grant money up to half of the grant you received, and a grant overpayment of $50 or less is waived. With $3,697 of Pell, the first $1,848.50 of your grant share is protected, so the example owes $0 in grant.
Three changes that move the answer
- Withdraw on day 62 instead of day 53: the term is 61.4% done, all aid is earned, and you owe $0.
- Same day 53, but school charges are $2,000 (a community college): the school returns $950 and that is the balance left on your account.
- A school that refunds 50% of tuition on that day: the $2,660 shrinks by half of the charges, to $0 in this case.
How to use the page
Open your school's academic calendar and count the calendar days from the first day of the term to the last, counting both ends. Count the days of any break that runs five days or longer, including the weekend days that touch it. Then count the days from the first day to the day you would withdraw. Copy the Pell Grant and Direct Loan amounts paid this term from your award letter or student account, and the tuition, fees and campus housing billed. The result updates as you type, in your browser. Nothing is sent anywhere.
Before you submit a withdrawal form, ask your financial aid office for its official date and your school's refund schedule, and check them against your result. Dropping only some classes is a different rule (your Pell Grant can be recalculated). This page covers withdrawing from all of them.
15 seconds — what it actually does
Questions people ask
What does this student planner calculate?
It finds the day in your term when you have earned 100% of your federal aid, and what you owe if you withdraw from all classes before it. Example: a 110-day fall 2026 term with a 9-day Thanksgiving break, withdrawing on day 53 with $3,697 Pell and $2,720 loans leaves a $2,660.00 unpaid school balance. Waiting until day 61 leaves $0.
Who is this for?
US college and community-college students who get a Pell Grant or Direct Loans and are thinking about withdrawing from every class this term, and the parents who pay the bill. It applies to credit-hour terms such as fall 2026 or spring 2027. Dropping only some classes is a different rule: your Pell Grant may be recalculated instead.
Why not just use a planner app or ask a chatbot?
Planner apps track assignments and due dates, not the 60% day under 34 CFR 668.22. Chatbots often count every calendar day. The rule removes scheduled breaks of at least five consecutive days from both the term total and the days you completed, so the real 60% day falls later than a plain count suggests.
What do I get for free?
The whole check for one term runs in your browser: share of the term completed, aid earned, unearned aid, what the school returns, any Pell Grant you owe after the 50% protection, the unpaid balance on your account, and how many days you would have to wait. Your numbers never leave your device. Nothing is locked.
What does it cost compared with other options?
The free check costs nothing. The .xlsx is a one-time $21 payment, not a subscription, and keeps the same 12 formulas offline for every term. A planner such as Prepwise Student Planner App sells on Whop for $17.50 and organises classes, but it does not compute the federal Return of Title IV Funds amounts.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.