· ReadyStack
Worked example
Real numbers from this tool, line by line.
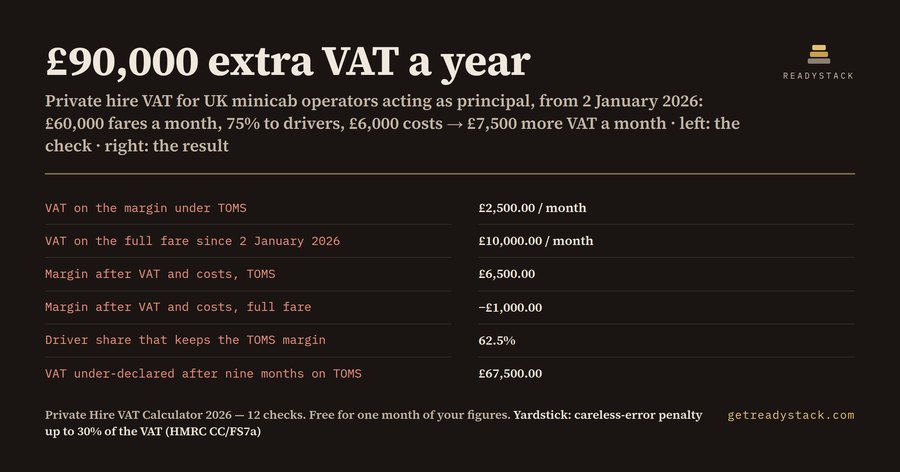
£90,000 extra VAT a year: that is the bill for a UK private hire operator acting as principal, with £60,000 of fares a month and 75% paid to drivers, once VAT moves from the margin to the full fare. Here is the month, worked through on the calculator:
| Check | Result |
|---|---|
| Margin after driver pay (£60,000 − £45,000) | £15,000.00 |
| VAT on the margin under TOMS (1/6 of £15,000) | £2,500.00 |
| VAT on the full fare (1/6 of £60,000) | £10,000.00 |
| Extra VAT per month | £7,500.00 |
| Margin after VAT and £6,000 running costs, TOMS | £6,500.00 |
| Same margin on the full-fare basis | −£1,000.00 |
The operator goes from £6,500 a month to a £1,000 monthly loss without a single fare or driver changing.
Why this happened on 2 January 2026
After the Upper Tribunal ruled in Bolt (March 2025) that private hire journeys could fall inside the Tour Operators' Margin Scheme, some operators that act as principal started paying VAT only on what they kept after paying the driver. HMRC disagreed and appealed. At Budget 2025 the government amended section 53 of the VAT Act 1994 instead: from 2 January 2026, suppliers of taxi and private hire journeys are not tour operators for TOMS, unless the journey is sold with accommodation or other principal travel services. HMRC's policy paper puts the effect at £725 million in 2026-27.
It does not touch operators acting as disclosed agent for the driver, or a cab hailed in the street. It does touch London PHV operators, who must act as principal, and any operator taking account work as principal.
The second number: VAT already under-declared
If your returns since January still used TOMS, the gap is already on the books. Nine months at £7,500 is £67,500. VAT Notice 700/45 lets you fix errors on the next return only up to £10,000, or up to £50,000 if that is not more than 1% of box 6. £67,500 is over £50,000, so it is method 2: a separate disclosure. HMRC factsheet CC/FS7a sets a careless-error penalty of 0% to 30% if you tell HMRC first, and 15% to 30% if HMRC finds it. At 30% that is £20,250.
What brings the margin back
The calculator answers two questions. At today's fares, a driver share of 62.50% restores the £6,500 margin. With driver pay held in pounds, a 15% fare rise does the same. Your contracts and passengers decide which is possible; the arithmetic just shows the size of each.
Why a VAT calculator or the HMRC brief is not enough
A free VAT calculator takes 20% of one price. HMRC's brief explains the rule and gives no figures for your business. Neither splits your fare into driver pay and margin, compares the two VAT bases, nets off your running costs, or tells you the driver share that keeps you in profit.
Try it on your figures
The free page runs all 12 checks for one month of your figures, in your browser, with nothing uploaded: type fares, driver share, running costs and months on TOMS. The workbook adds a 2026 VAT periods sheet, one row per month with quarter totals and the Notice 700/45 test, and a Commission planner that lays out 6 driver-share and fare combinations side by side.
15 seconds — what it actually does
Questions people ask
What does the private hire VAT calculator work out?
It splits your monthly fares into driver pay and your margin, then compares VAT on the margin under TOMS with VAT on the full fare that applies from 2 January 2026. With £60,000 of fares and 75% to drivers, VAT rises from £2,500 to £10,000 a month: £90,000 more a year, and a £6,500 monthly margin becomes a £1,000 loss.
Which operators does the 2 January 2026 change hit?
Private hire and taxi operators that supply journeys as principal or as an undisclosed agent, which London PHV operators must do. HMRC's Brief 8 (2025) says operators acting as disclosed agent for the driver, drivers paid directly by passengers, and tour operators selling a taxi transfer with a hotel or flight package are not affected.
Why not use a free VAT calculator?
A free VAT calculator takes 20% of one price. It does not split each fare into driver pay and your margin, compare the TOMS margin basis with the full-fare basis, show what is left after your running costs, or tell you which driver share or fare rise brings the margin back. HMRC's brief gives the rule but no figures for your business.
What is free on this page and what is in the paid file?
Every check is free on the page for one month of figures: both VAT bases, the extra VAT per month and year, margin after costs, the driver share and fare rise that keep your margin, VAT under-declared since January, the Notice 700/45 method and the penalty exposure. The paid .xlsx adds a month-by-month VAT periods sheet and a 6-scenario commission planner you keep and edit.
What is at stake if my returns since January used TOMS?
In the worked example, 9 months on TOMS leaves £67,500 of VAT under-declared. That is above £50,000, so VAT Notice 700/45 needs method 2, a separate disclosure to HMRC rather than an adjustment on the next return. A careless error carries a penalty of 0% to 30% if you disclose unprompted, or 15% to 30% if HMRC finds it first.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.