· ReadyStack
Worked example
Real numbers from this tool, line by line.
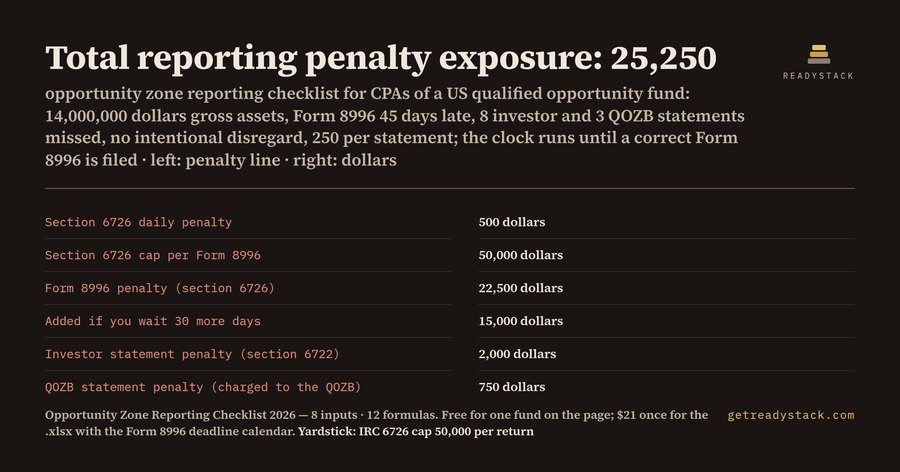
A qualified opportunity fund with 14,000,000 dollars of gross assets that files its Form 8996 45 days late or incomplete now faces 25,250 dollars of reporting penalties, and that is the number CPAs who prepare QOF returns should check before the first 2027 deadline.
| Result | Value |
|---|---|
| Section 6726 daily penalty | 500 dollars |
| Section 6726 cap per Form 8996 | 50,000 dollars |
| Form 8996 penalty (section 6726) | 22,500 dollars |
| Days until the cap is reached | 100 |
| Added if you wait 30 more days | 15,000 dollars |
| Investor statement penalty (section 6722), 8 statements | 2,000 dollars |
| QOZB statement penalty, 3 statements | 750 dollars |
| Total reporting penalty exposure | 25,250 dollars |
The statement penalties use the statutory 250 dollars per statement before the yearly inflation adjustment; type the figure the IRS publishes for your year.
Why this is new
Before OBBBA, no information reporting penalty applied to a fund that skipped Form 8996. Pub. L. 119-21 section 70421(d) added IRC 6039K (the fund's annual return), 6039L (statements from each QOZB to its fund) and 6726 (the penalty). The new rules cover taxable years beginning after 2025-07-04, so a calendar-year 2026 partnership fund files the first exposed Form 8996 by 2027-03-15, or 2027-09-15 on extension.
How the penalty is built
Section 6726 charges 500 dollars for each day a complete, correct return is missing. The cap is 10,000 dollars per return, or 50,000 dollars when gross assets on the last day of the tax year exceed 10,000,000. Intentional disregard raises the daily amount to 2,500 dollars and the caps to 50,000 and 250,000. A small fund therefore reaches its cap after 20 days, a large one after 100. The proposed regulation's own example: a fund files 15 days late and owes 500 x 15 = 7,500 dollars.
The clock stops only on the day a complete, correct Form 8996 is filed. A paper filing where electronic filing is required, or a return missing required fields, counts as a failure under the proposed rules.
The checklist itself
Fund level: certification facts, the investment-standard result for both testing dates, the valuation method, and any voluntary decertification. Each QOZB: name, address and TIN, your interest and its value on the testing dates, the QOZB attestation or cure period, and per census tract the address, NAICS code, owned and leased property, residential units, average monthly FTEs, first acquisition date, substantial improvement start and working capital safe harbor end. Each investor with a disposition: identity, acquisition and disposition dates, amount contributed, interests held and disposed of.
Dates to diary
QOZB statements are due on the 1st day of the second month after the QOZB year end: 2027-02-01 for a calendar year. Investor statements are due by March 1. Form 8996 goes with the fund return, extensions included. Comments on the proposed rules close 2026-10-16 and the public hearing is set for 2026-11-05.
Run your own fund
Open the free page, type your gross assets, days late and statement counts, and read your own total. Reasonable cause under section 6724 can still waive a penalty, so file the correction first and write the explanation second.
15 seconds — what it actually does
Questions people ask
What does the opportunity zone reporting checklist calculator work out?
It takes 8 inputs: gross assets, days late, missing investor statements, missing QOZB statements, intentional disregard, per-statement amount, tax year end, entity type. It runs 12 formulas: daily rate, cap, Form 8996 penalty, days to cap, 30 more days, investor penalty, QOZB penalty, total, and due dates for QOZB statements, investor statements, Form 8996 and extended Form 8996.
Who is this for?
US CPAs, tax managers and fund controllers who prepare Form 8996 for a qualified opportunity fund, whether it files Form 1065 or Form 1120, and the accountants of qualified opportunity zone businesses that now owe their fund a written statement. It is built for the first returns under the OBBBA reporting rules, for calendar-year 2026 funds due in 2027.
Why not rely on tax software or a chatbot?
Tax software fills in Form 8996 but does not price a late or incomplete one. Before OBBBA no information reporting penalty applied to a missing Form 8996, and many chatbot answers still say so. Section 6726 now charges 500 dollars a day, and its cap moves from 10,000 to 50,000 once year-end gross assets pass 10,000,000 dollars.
What is free?
The whole penalty answer for one fund and one tax year, on the page, with no account. You type gross assets, days late, missing investor statements, missing QOZB statements, intentional disregard and the per-statement amount. The page returns all 8 penalty results and shows the three-part reporting checklist. Nothing on the page is cut short.
What does the full version add, and what does a mistake cost?
The paid .xlsx keeps the same 8 formulas in the fund's tax file and adds a 4-date deadline calendar for any tax year end: QOZB statements, investor statements, and Form 8996 with and without a 6-month extension. The proposed regulation's own example is a Form 8996 filed 15 days late: 500 x 15 = 7,500 dollars.
When do these rules change next?
The proposed regulations (Federal Register 2026-18574) take comments until 2026-10-16, with a public hearing set for 2026-11-05. The due dates and furnishing rules apply once final regulations are published. The 500-dollar daily amount and the caps come from the statute and are adjusted for inflation each year under section 6726(d).
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.