· ReadyStack
Worked example
Real numbers from this tool, line by line.
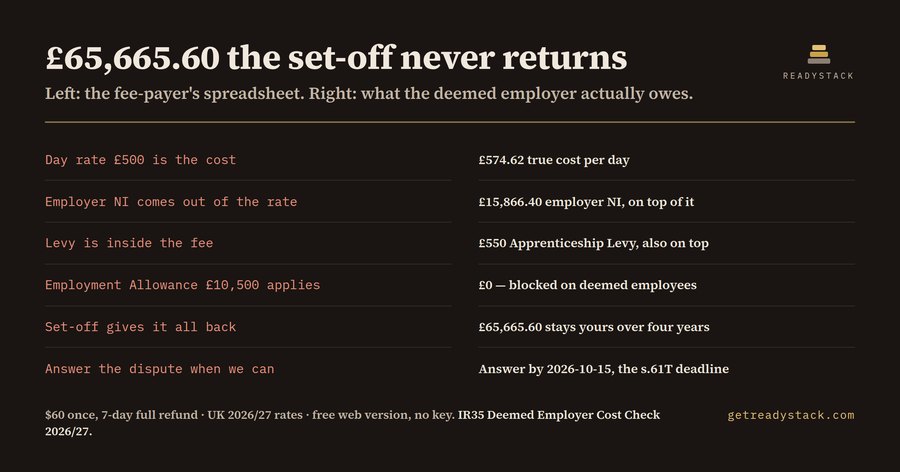
£65,665.60 — UK recruitment agency fee-payers, one £500-a-day contractor, four assessable years at £16,416.40 each. That is the run, straight off the free web page:
| Output | Result |
|---|---|
| Deemed direct payment (PAYE base) | £110,000.00 |
| Employer NI at 15% — your cost, on top | £15,866.40 |
| Apprenticeship Levy at 0.5% | £550.00 |
| Employment Allowance relief available | £0.00 |
| Cost on top of the agreed rate, per year | £16,416.40 |
| True cost per day | £574.62 |
| Outside the set-off if status is overturned, over four years | £65,665.60 |
| s.61T deadline to answer the dispute | 2026-10-15 |
Inputs: £500 a day, 220 days engaged, no VAT inside the invoiced amount, £0 direct materials, annual pay bill over £3m, determination disputed, four years HMRC can assess, representations received 1 September 2026.
Eight figures out, and the £65,665.60 is not the tax bill. It is only the slice of the tax bill that the off-payroll set-off rules refuse to hand back, totalled across the four years.
Since 6 April 2024 HMRC has been able to offset tax already paid by a contractor's personal service company against the PAYE liability of the deemed employer. For income tax and employee National Insurance it works. But the legislation permits set-off of income tax and employee NICs only. Arrears of employer NICs, and the Apprenticeship Levy where it is due, sit outside the mechanism entirely. They stay with the fee-payer, in full, for every year HMRC can assess.
Here is where the £16,416.40 a year comes from. The deemed direct payment — the PAYE base Chapter 10 ITEPA 2003 defines — is £110,000. Employer secondary Class 1 National Insurance for 2026/27 runs at 15% above a secondary threshold of £5,000 a year, which is £96 a week and frozen until 2030/31. Across 44 working weeks that threshold shelters £4,224, so the agency owes 15% of £105,776: £15,866.40. An agency with an annual pay bill over £3m adds the Apprenticeship Levy at 0.5% of the deemed payment, another £550.
That £16,416.40 sits on top of the agreed rate, not inside it. A deemed employer cannot lawfully deduct employer NI or the Levy from the contractor's rate to recover it. So the £500-a-day contractor is a £574.62-a-day contractor, and the margin the agency priced the placement on was never there.
Then there is the line most spreadsheets get wrong in the other direction. The Employment Allowance is £10,500 in 2026/27, and it cannot be set against payments to deemed employees. Payroll templates and chatbots apply it anyway, because it applies everywhere else in the same payroll. On this engagement the relief available is £0.
Under section 61T ITEPA 2003, when a worker makes representations against a Status Determination Statement, the client has 45 days beginning with the day the representations are received to either confirm the conclusion with reasons or issue a new SDS. Miss that and the client itself is treated as the deemed employer. Representations received on 1 September 2026 must be answered by 15 October 2026. That date is not on any calendar until somebody puts it there.
HMRC's CEST tool answers one question — inside or outside — and returns a status. It never returns a pound figure, it does not apply employer NI or the Levy, and it is silent on how much of an overturned determination you will actually eat.
IR35 Deemed Employer Cost Check 2026/27 is a browser extension and a free web page sharing one engine. Eight inputs in, eight figures out — the table above is the whole of it. All eight are free, unlimited, and nothing you type leaves your machine.
The paid layer sits on a different axis, not a bigger number. For $60 the key exports the liability schedule as a .csv you own and sets a browser alarm on the s.61T date. For comparison, a per-contract IR35 status review from a UK contractor accountant is quoted at £200 to £800 in September 2026 price guides — it comes back with a status, not a liability.
Questions people ask
What does this actually work out?
It takes one inside-IR35 engagement and returns the numbers a fee-payer has to put through payroll: the deemed direct payment after VAT and materials, employer National Insurance at 15% above the GBP 96 weekly secondary threshold, the 0.5% Apprenticeship Levy, the true cost per day, and the amount the April 2024 set-off will not give back if HMRC overturns the status.
Who is this for?
UK recruitment agency fee-payers, contractor payroll bureaux and end clients who sit in a labour supply chain under Chapter 10 ITEPA 2003. If you are the lowest party in the chain above the worker's intermediary, you are the deemed employer and these are your numbers, not the contractor's.
Why is HMRC's free CEST tool not enough?
CEST answers one question: is this engagement inside or outside the off-payroll rules. It returns a status. It never returns a pound figure, it does not apply the 15% employer NI or the Apprenticeship Levy, and it says nothing about how much of an overturned determination the April 2024 set-off will actually return to you.
What is free and what does the key add?
Every calculation is free, unlimited and unlocked: all eight outputs, including the set-off gap and the s.61T answer date. The $60 key adds a different axis, not a bigger number. It exports the liability schedule as a .csv you own and sets a browser alarm on the 45-day dispute deadline.
What would this cost me from a person?
A per-contract IR35 status review from a UK contractor accountant is quoted at GBP 200 to 800 in September 2026 price guides, and it comes back with a status rather than a liability. Pricing employer NI, the Levy and the set-off gap is a separate employment-tax exercise on top of that fee.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.