· ReadyStack
Worked example
Real numbers from this tool, line by line.
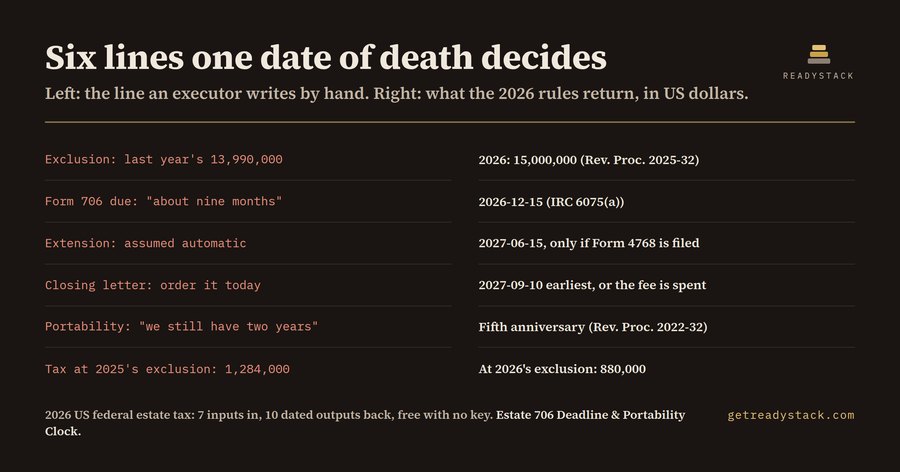
An $18,400,000 estate with $1,200,000 of deductions, from a death on 2026-03-15, owes $880,000 of US federal estate tax - and the return is due 2026-12-15. Move that same death back one year to 2025-03-15 and the tax is $1,284,000. Nothing about the estate changed. Only the basic exclusion did: $13,990,000 for 2025, $15,000,000 for 2026.
That $404,000 gap is why estate attorneys, trust officers and fiduciary CPAs in the United States cannot take a 2026 filing calendar from a general-purpose chatbot. Section 70106 of the One Big Beautiful Bill Act, signed 2025-07-04, amended IRC 2010 to set the basic exclusion at $15,000,000 beginning in 2026 and deleted the sunset that had been on the books since 2017. The IRS confirmed the figure in Rev. Proc. 2025-32. Any model or article written before that still describes 2026 as the year the exclusion falls - which flips the answer to whether the estate owes anything at all.
The Estate 706 Deadline & Portability Clock is a Chrome extension, and the same calculation also runs as a free web page. You give it seven things: the date of death, the gross estate plus adjusted taxable gifts, the marital/charitable/debt deductions, any DSUE ported from a predeceased spouse, whether the automatic Form 4768 extension was elected, the date Form 706 was actually filed, and today's date. It returns ten, and every one of them is a date or a dollar someone would otherwise derive by hand.
The filing calendar first. IRC 6075(a) puts Form 706 due nine months after death, so 2026-03-15 becomes 2026-12-15. The automatic six-month extension on Form 4768 - which has to be filed on or before that original due date - carries it to 2027-06-15. From 2026-09-14 that leaves 274 days. Slip it and IRC 6651(a)(1) adds five percent of the tax for each month or fraction of a month, capped at twenty-five percent: on $880,000 of tax, $44,000 for month one.
Then the two dates people get wrong most often. The IRS asks that a request for Letter 627, the estate tax closing letter, wait at least nine months after Form 706 is filed. Filed 2026-12-10, that is 2027-09-10 at the earliest - and the request carries a $56 Pay.gov user fee, set by T.D. 10031 in May 2025, down from the $67 in force since October 2021. Ordering it early spends the fee without getting the letter any sooner.
The other is portability. An estate under the filing threshold has no Section 6018(a) filing requirement, so a surviving spouse's DSUE election is easy to postpone and then lose. Rev. Proc. 2022-32 extended the simplified late-election window from two years to five, measured from the date of death. Run the same 2026-03-15 death with a $9,200,000 gross estate and $400,000 of deductions and the tool stops asking about tax - there is none - and instead dates that window: 2031-03-15. When a timely 706 is required, it says so rather than printing an anniversary nobody may rely on.
All of that is the free layer. No key, no sign-in, no limit, no watermark, no locked field: the popup and the web page both compute every figure above for any inputs you type, and nothing about the decedent or the estate leaves the browser tab. The $60 licence key is for two different jobs, not for more arithmetic - taking the result with you as a .csv checklist for the client file or the docket, and making it repeat as Chrome alarms that fire ahead of each date once the tab is closed.
For scale: a Form 706 starts around $2,500 and estate CPAs bill $150 to $400 an hour. The calendar is not the expensive part of an estate administration. Getting one of its four dates wrong is.
Questions people ask
What does this actually do?
You type a date of death, a gross estate figure and the date Form 706 was filed. It returns the nine-month Form 706 due date under IRC 6075(a), the six-month Form 4768 extended date, the earliest date you may order the IRS closing letter on Pay.gov, the five-year late-portability anniversary, the year-of-death basic exclusion, and the estimated tax at the 40 percent top rate.
Who is it for?
US estate attorneys, trust officers, fiduciary CPAs and individual executors who are administering a decedent's estate in 2026 and need the federal filing calendar for that particular death date. It is written for the person who has the date of death in front of them and has to put four dates in a file, not for general estate planning.
Why not just ask a chatbot or use a free date calculator?
A generic date calculator does not know the 2026 basic exclusion is $15,000,000. Models trained before the One Big Beautiful Bill Act was signed in July 2025 still repeat the repealed sunset of roughly seven million dollars, which flips whether an estate owes tax at all. This tool holds the year-of-death figure from Rev. Proc. 2025-32 and shows its arithmetic.
What is free and what needs the key?
Everything the calculator computes is free with no key, no limit and no watermark, in the popup and on the free web page. The $60 key unlocks two different things, not more calculation: exporting the dated checklist as a .csv you can file, and Chrome alarms that fire ahead of each deadline after the tab is closed.
What would this cost otherwise?
Preparing a Form 706 starts around $2,500 and estate CPAs bill roughly $150 to $400 an hour, so re-deriving a filing calendar by hand is billable time. The IRS closing letter is a separate $56 Pay.gov user fee set by T.D. 10031 in May 2025, and it is wasted if the request is filed before the nine-month wait is up.
Does it send my estate figures anywhere?
No. The calculation runs entirely in your browser tab; nothing about the decedent, the estate value or the dates leaves the machine. The only outbound request the extension ever makes is a licence-key check against api.polar.sh when you use the paid export or alarm features, and that request carries the key and nothing else.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.