· ReadyStack
Worked example
Real numbers from this tool, line by line.
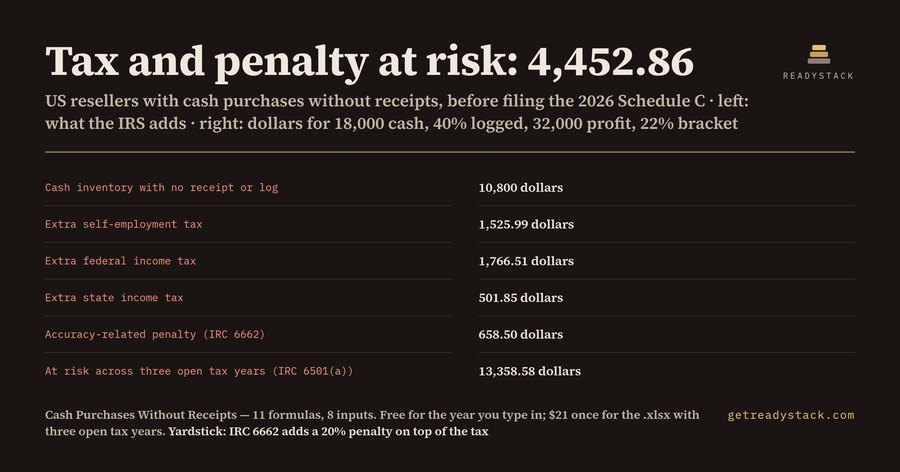
Tax and penalty at risk: 4,452.86 dollars. That is what a US reseller on Schedule C, the sports card or flea-market flipper who paid 18,000 dollars in cash for inventory this year and can back only 40% of it with a log and a bank withdrawal, owes if the undocumented cost is disallowed.
| Result | Value |
|---|---|
| Cash inventory with no receipt or log | 10,800 dollars |
| Self-employment tax as filed | 4,521.46 dollars |
| Self-employment tax if the cash cost is disallowed | 6,047.45 dollars |
| Extra self-employment tax | 1,525.99 dollars |
| Extra federal income tax | 1,766.51 dollars |
| Extra state income tax | 501.85 dollars |
| Accuracy-related penalty (IRC 6662) | 658.50 dollars |
| Tax and penalty at risk | 4,452.86 dollars |
The example assumes 32,000 dollars of Schedule C net profit as filed, no W-2 wages, a 22% federal bracket, the 20% QBI deduction and a 5% state rate. Change any of them on the page and every line moves.
Why one undocumented dollar costs about 41 cents
Cost of goods sold is the biggest deduction a reseller has. When it goes, profit goes up by the same amount, and three taxes hit it at once. Self-employment tax takes 15.3% of 92.35% of the extra profit: 12.4% for Social Security up to the 184,500-dollar 2026 wage base and 2.9% for Medicare with no cap. Federal income tax takes your bracket, after half of the extra SE tax is deducted and after the 20% QBI deduction. Your state takes its own rate. Then IRC 6662 adds a 20% accuracy-related penalty on the federal underpayment when it comes from negligence or a substantial understatement. In the example, 4,452.86 dollars on 10,800 undocumented dollars is 41.23%.
When W-2 wages change the answer
If you also have a day job, your wages use up the Social Security wage base first. With 180,000 dollars of W-2 wages, 30,000 dollars of resale profit and a 24% bracket, only 4,500 dollars of room is left under the base, so the extra SE tax drops to 289.24 dollars. The federal income tax rises to 2,045.83 dollars, and the total at risk is 3,334.86 dollars. A flat 15.3% calculator gets this case wrong.
What a record looks like when the seller gives no receipt
IRS Publication 583 says purchase records should show the amount paid and that it was for purchases. With cash, build that record yourself: a log line the same day with the date, seller or show table, items and price; cash taken from your business account so each log line matches an ATM or bank withdrawal; photos and messages where the price was agreed. Inventory cost is not one of the IRC 274(d) items (travel, gifts, listed property) that must be proved in strict detail, so courts can accept a reasonable reconstruction under the Cohan rule. Without one, the whole cost can be disallowed.
Logging more changes everything
The same reseller who buys 5,000 dollars in cash and logs 90% of it has 500 undocumented dollars and 206.15 dollars at risk. The page lets you see that difference with your own figures before you file.
Free and paid
The page gives the whole one-year answer free, with no account. The .xlsx workbook keeps the same 11 formulas for your records and adds the cost per undocumented dollar and the exposure across the three tax years the IRS can normally assess under IRC 6501(a): 13,358.58 dollars in the example.
15 seconds — what it actually does
Questions people ask
What does the cash purchases without receipts calculator work out?
It runs 11 formulas: cash with no receipt or log, room under the 2026 Social Security wage base, SE tax as filed, SE tax if the cash cost is disallowed, extra SE tax, extra federal income tax, extra state income tax, the IRC 6662 penalty, total at risk, cost per undocumented dollar, and the three-open-year total.
Who is this for?
US resellers who pay cash for inventory and get no receipt: sports card buyers at shows, thrift and flea-market flippers, estate-sale and garage-sale buyers who file Schedule C. It also suits bookkeepers whose clients hand them a year of cash buys with nothing but a bank statement and a memory.
Why not use a free tax calculator?
Free tax calculators assume every expense you enter is allowed. None prices the case where cash inventory with no receipt is disallowed, so none adds the 15.3% self-employment tax, the 184,500-dollar Social Security wage base, the QBI effect and the 20% IRC 6662 penalty together on the same dollars.
What is free?
The whole one-year answer on the page, with 8 inputs: cash inventory purchases, share backed by a log and bank withdrawal, Schedule C net profit, W-2 wages, federal bracket, QBI deduction rate, state income tax rate and the 6662 penalty rate. It shows the first 9 formulas, ending with tax and penalty at risk. No account is needed.
What does the full version add, and what does a mistake cost?
The paid .xlsx workbook keeps the same formulas for your records and adds the cost per undocumented cash dollar and the exposure across the three tax years the IRS can normally assess under IRC 6501(a). A disallowed deduction alone draws a 20% accuracy-related penalty under IRC 6662 on top of the tax.
When do these numbers change next?
The Social Security wage base of 184,500 dollars applies to 2026 earnings only. A new base takes effect on 2027-01-01, announced by the Social Security Administration each October. The 15.3% self-employment rate, the 92.35% factor and the 20% IRC 6662 penalty are set by statute and do not change on a yearly schedule.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.