· ReadyStack
Worked example
Real numbers from this tool, line by line.
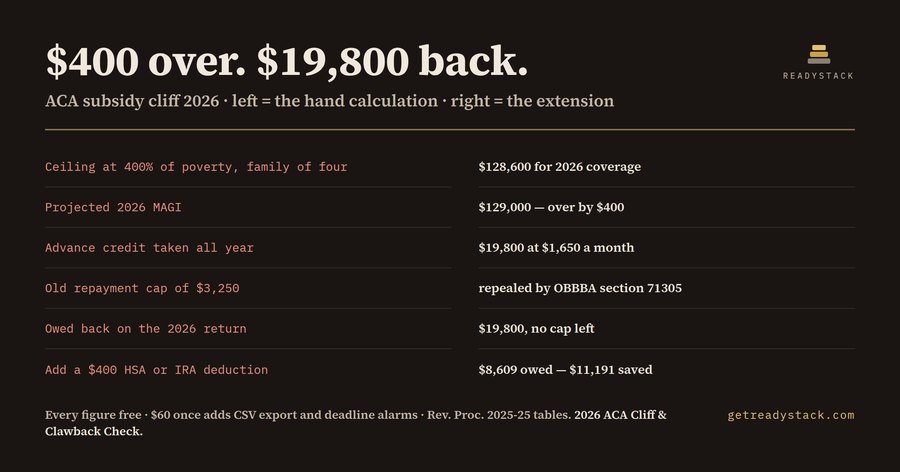
A US tax preparer's client came in $400 over the 2026 subsidy cliff and owed back all $19,800 of advance premium tax credit. The client is a self-employed couple in the lower 48 with two children, projected 2026 MAGI of $129,000, a benchmark silver premium of $24,000 a year, and $1,650 a month of advance credit taken for all 12 months.
Here is why $400 costs $19,800. The 2026 Marketplace year uses the 2025 HHS poverty guidelines: $15,650 for one person in the lower 48 and DC, plus $5,500 for each additional person. A household of four is $32,150, so 400% of the federal poverty line is $128,600. At $129,000 the household is over the line by $400, and above 400% FPL the premium tax credit for 2026 is zero. The enhanced subsidies that removed that cliff expired on 31 December 2025.
The second half is newer and catches even careful preparers. Through the 2025 return, a client who underestimated income repaid only a limited amount of the excess: section 36B(f)(2)(B) capped repayment at $1,625 for a single filer and $3,250 for everyone else. Section 71305 of the One Big Beautiful Bill Act repealed those caps for tax years beginning after 31 December 2025. On the 2026 return there is no cap. Every advanced dollar comes back.
The useful part is what a last deductible dollar buys. Subtract a $400 HSA, IRA or SEP contribution from MAGI and the household lands at exactly $128,600, which is 400.00% of FPL. The applicable percentage there is 9.96% under Rev. Proc. 2025-25, so the expected contribution is $12,808.56 and the allowed credit is $11,191.44. The repayment falls from $19,800 to $8,608.56. A $400 deduction is worth $11,191. No client works that out in their head.
This is exactly the calculation a general-purpose chatbot gets wrong. Ask one today and it answers with American Rescue Plan rules: a 0% to 8.5% sliding contribution scale, no cliff above 400% FPL, and capped repayment. All three expired at the end of 2025. The 2026 applicable percentage table in Rev. Proc. 2025-25 starts at 2.10% below 133% FPL and runs through 3.14%, 4.19%, 6.60% and 8.44% to a flat 9.96% from 300% to 400% FPL. Free 2025 calculators still ship the old scale, which is why they quietly report a credit where 2026 gives none.
The 2026 ACA Cliff & Clawback Check is a browser extension for Chrome, Edge and Firefox that holds those three tables - the 2025 HHS poverty guidelines for all three state groups, the Rev. Proc. 2025-25 percentages, and the uncapped repayment rule - and returns ten figures from seven inputs. State group, household size, projected MAGI, benchmark premium, advance credit per month, months covered, and any deductible contribution still available go in. The poverty line, the percent of FPL, the 400% ceiling, the dollars above or below it, the applicable percentage, the expected contribution, the allowed credit, the repayment, the repayment after the contribution, and the amount that contribution saves come out.
Change the state group to Alaska and the same $129,000 household is fine: the Alaska poverty line for four is $40,190, the ceiling is $160,760, and the repayment is $8,648.40 instead of $19,800.
Every calculation is free, in the popup and in a browser page, with no key, no watermark and no run counter. The $60 key adds what happens after the answer: CSV export of every client run for the workpaper file, and alarms before the 15 January enrollment close and the 15 April filing date. A CPA charges $200 to $400 an hour for tax services in 2026; the projection itself is the cheap part, and the arithmetic is what goes wrong.
15 seconds — what it actually does
Full walk-through
Questions people ask
What does this extension actually do?
It takes a client's projected 2026 MAGI, household size and state group and returns the 400% federal poverty line ceiling, the dollars above or below it, the applicable percentage from Rev. Proc. 2025-25, the allowed premium tax credit, and the advance credit that must be repaid on the 2026 return now that the repayment caps are gone.
Who is it for?
US tax preparers, enrolled agents, CPAs and ACA brokers who run year-end income projections for self-employed and early-retiree Marketplace clients. It is built for the conversation where a client asks how much a December bonus, Roth conversion or good sales month will cost them in repaid subsidy.
Why not just ask a chatbot or use a free 2025 calculator?
Most free calculators and chatbot answers still run the enhanced-subsidy rules that expired on 31 December 2025: a 0% to 8.5% contribution scale, no cliff above 400% FPL, and capped repayment. OBBBA section 71305 deleted the $3,250 cap, so for 2026 all three are wrong. This tool ships the Rev. Proc. 2025-25 table, the hard cliff and uncapped repayment.
What is free and what needs the key?
Every calculation is free and unlimited, in the popup and in the browser page, with no watermark and no run counter. The $60 key adds ownership and repetition: CSV export of your client runs for the workpaper file, and alarms before the 15 January enrollment close and the 15 April filing date.
What would this cost done by hand?
A CPA charges $200 to $400 an hour for tax services in 2026, and a cliff projection means pulling the HHS poverty table, the Rev. Proc. 2025-25 percentages and the Form 1095-A totals before you can answer. One such meeting costs more than the $60 key, and the arithmetic is the part that goes wrong.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.